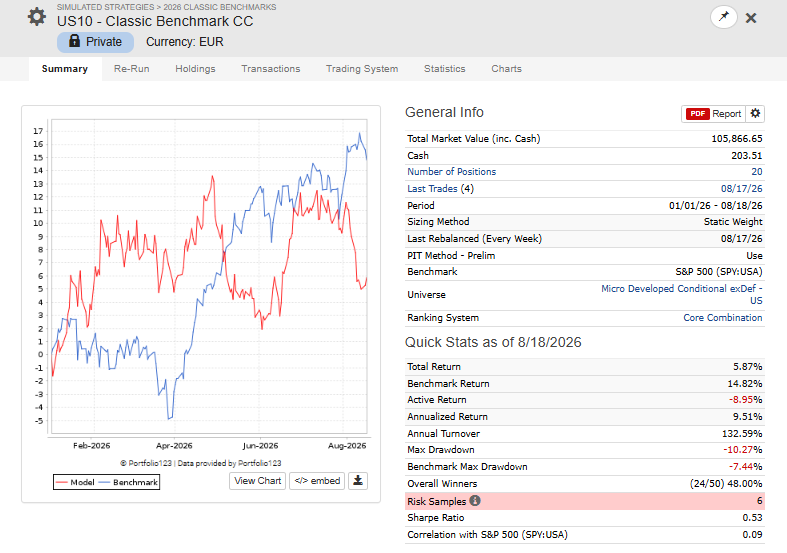
Failing US microcap strategies YTD

Hi guys,

First of all:
This is just an observation and I am curious. This is not a definitive conclusion or panic that something is changing. I know that concentrated illiquid strategies are volatile and pressing the boundary of concentration and turnover leads to a broader dispersion of outcomes and a higher risk of “getting fooled by randomness”. Who knows me from X already saw my posts whining about my US performance recently. Still, I’d like to get the opinion of the community. Do you guys see similar stuff?

Imo, 2026 is the most crazy year I have seen so far regarding microcap return as function of overall design questions:

  • Classic or AIFactor?
  • Which factors/features involved (Value, Mom, LowVol, etc.)?
  • 10, 20 or 50 stocks?
  • Universe (Allcap?, filtered Small&Micro?)
  • Daily, weekly or monthly, etc. rebalance?
  • Tight or wide rank tolerance?

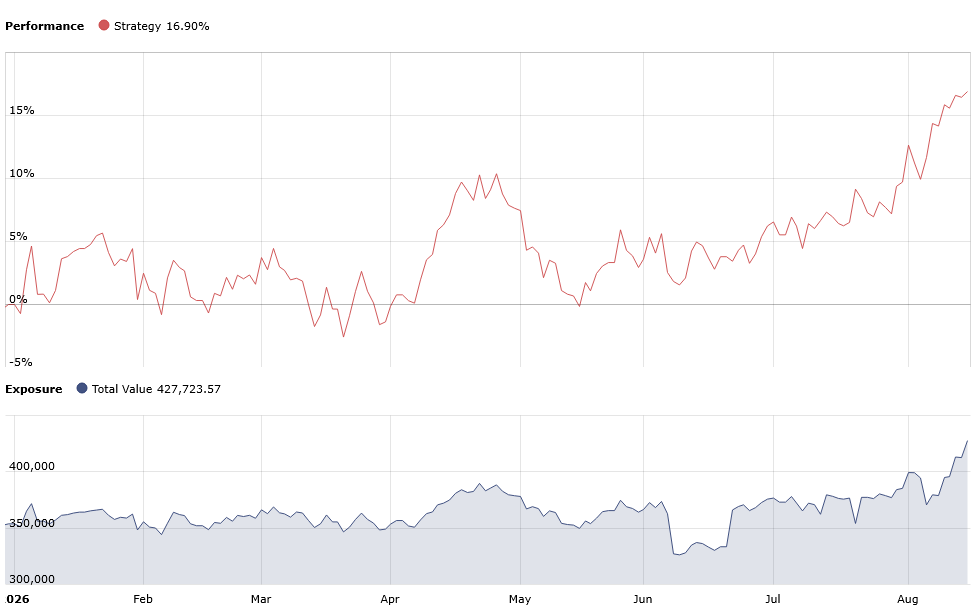
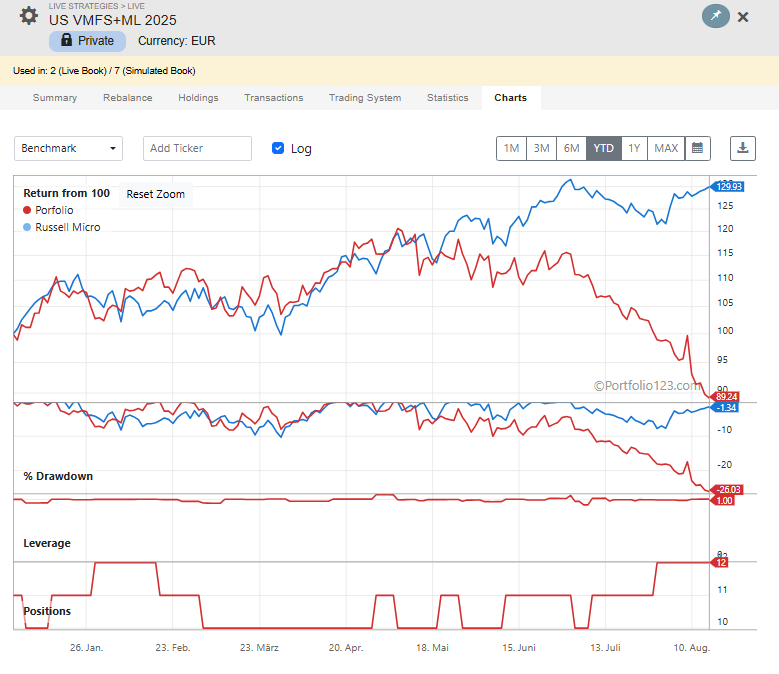
I run an AI-Factor+Value/Momentum Ranking system on a pure US microcap universe.

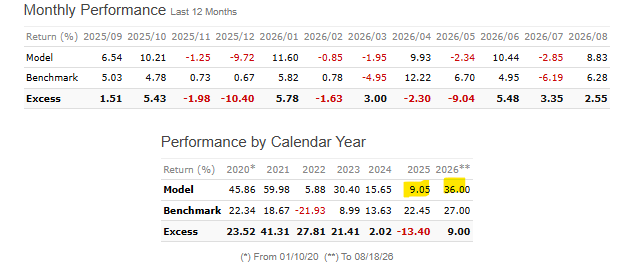
Live has been disastrous in July/August:
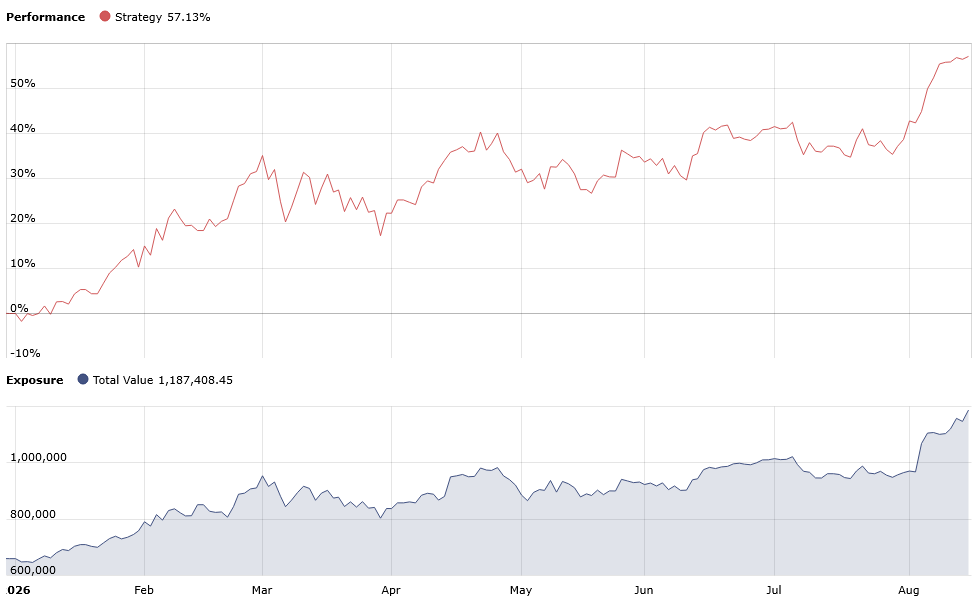
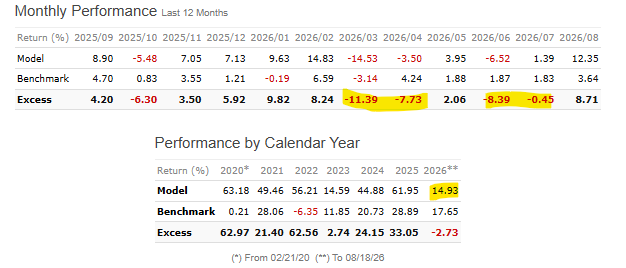
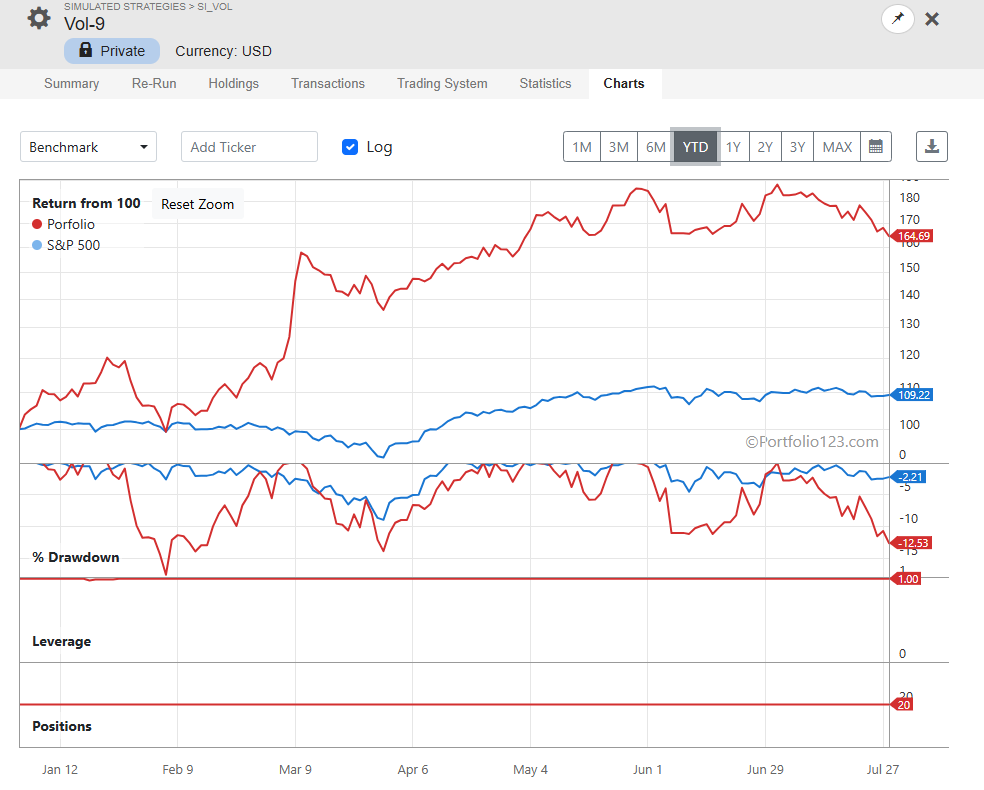
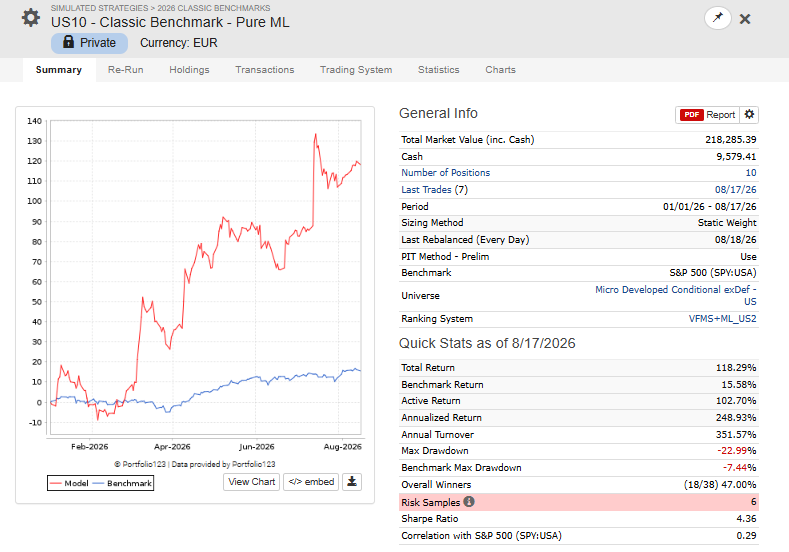
Somehow, a designer model version I created on the same principles is killing it recently:
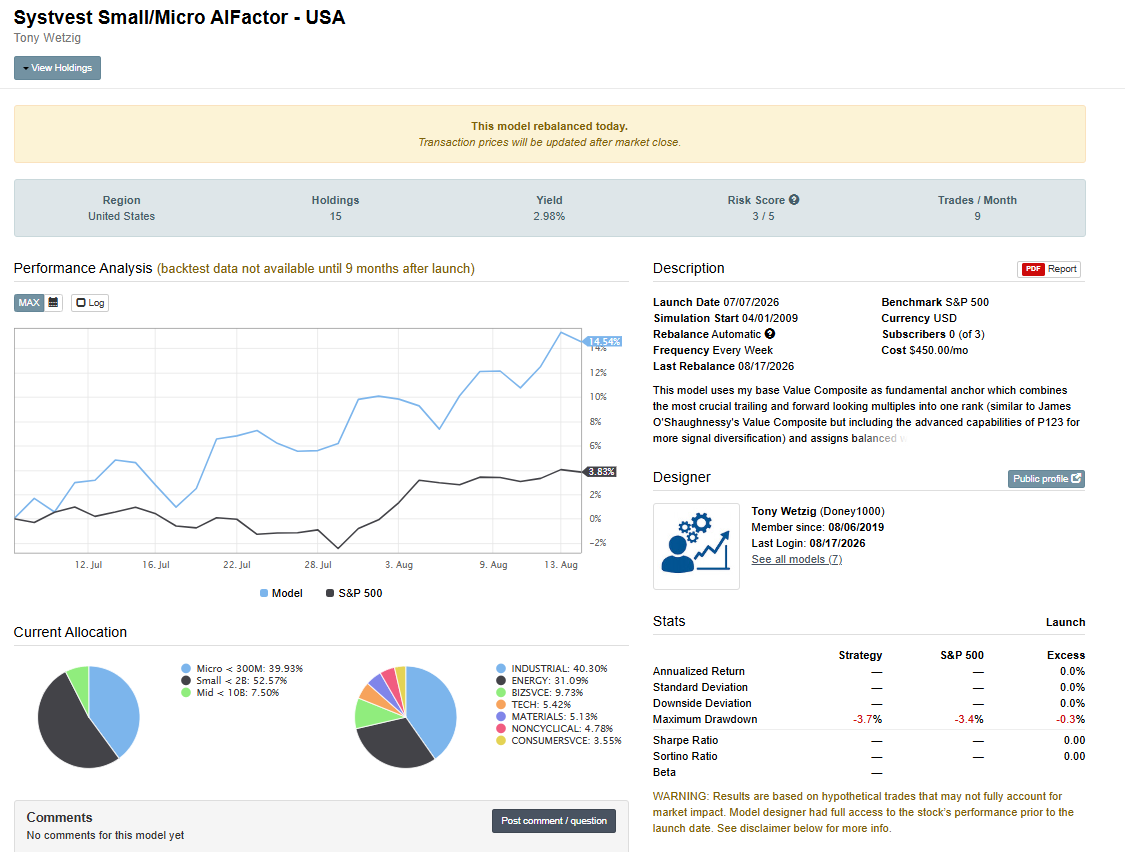
These are literally the same feature sets and ML algos just on slightly more liquid stocks (to match DM requirements) and 15 instead of 10 stocks.

Not judging if that’s a big or small difference, of course, it can have significant implications. I just find it fascinating. Also noticing that in other strategies.

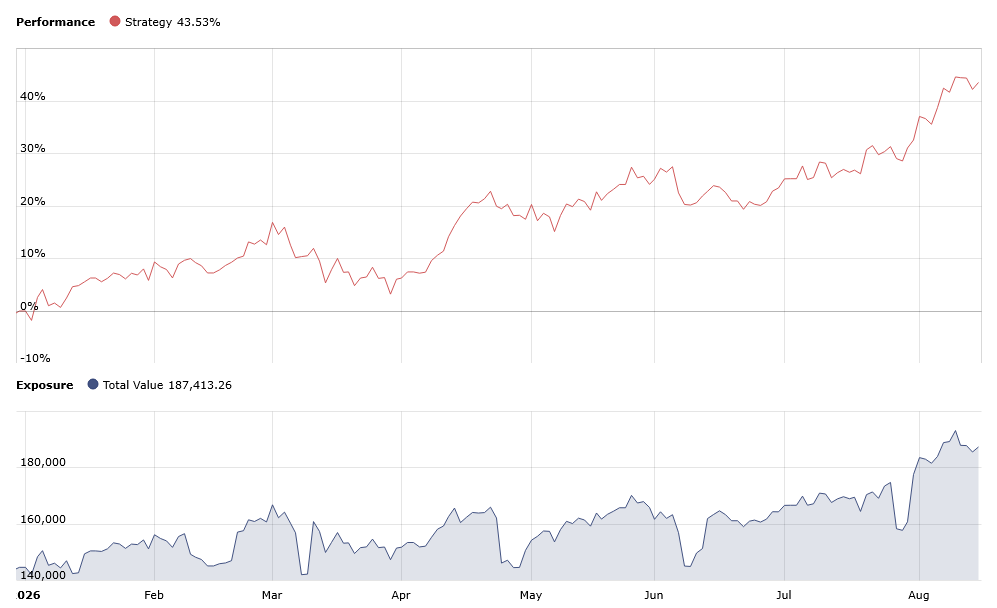
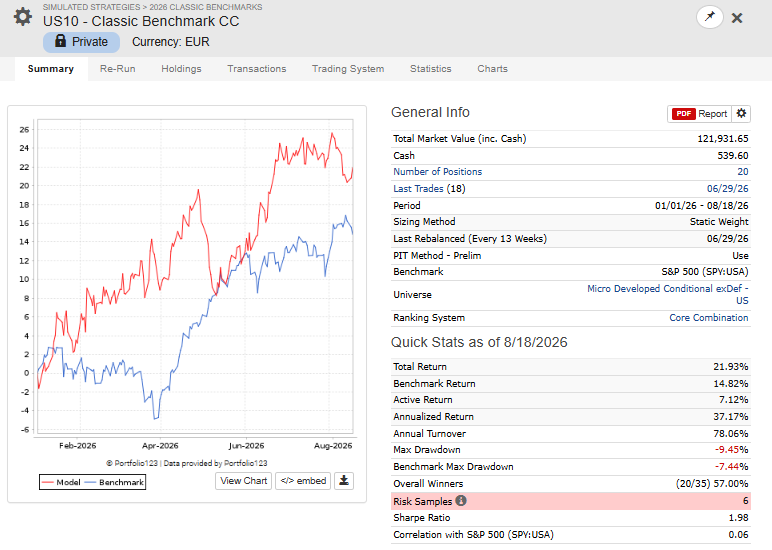
My universe + Core Combination, 20 stock, sell at RankPos > 50: Same collapse recently…
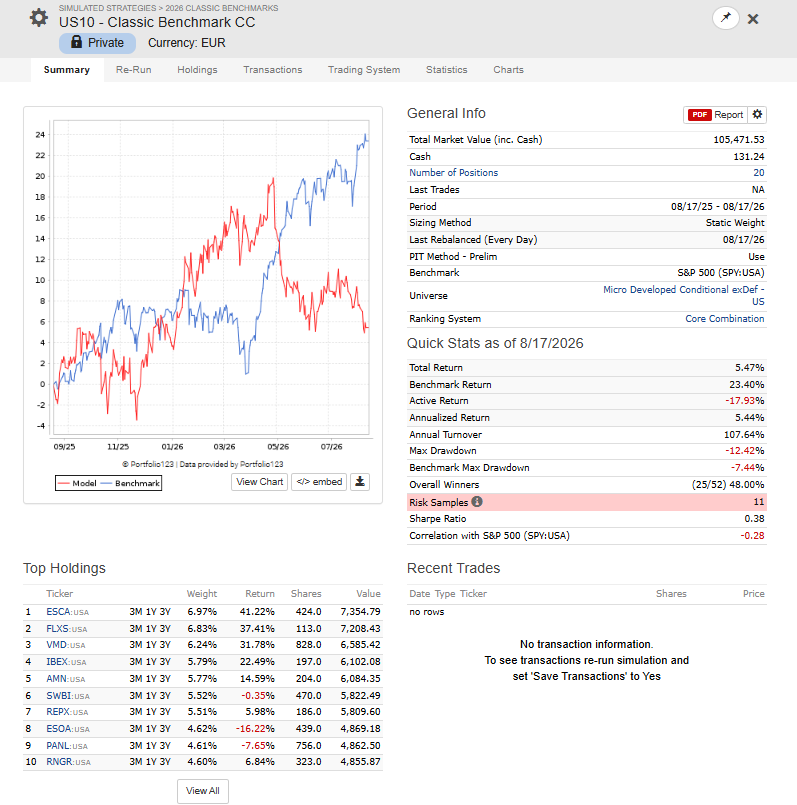
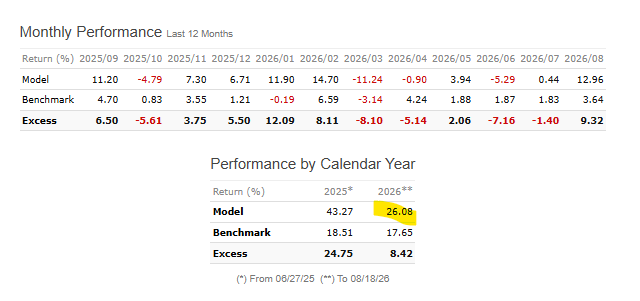
Also “small & microcap focus” has its toughest year ever:
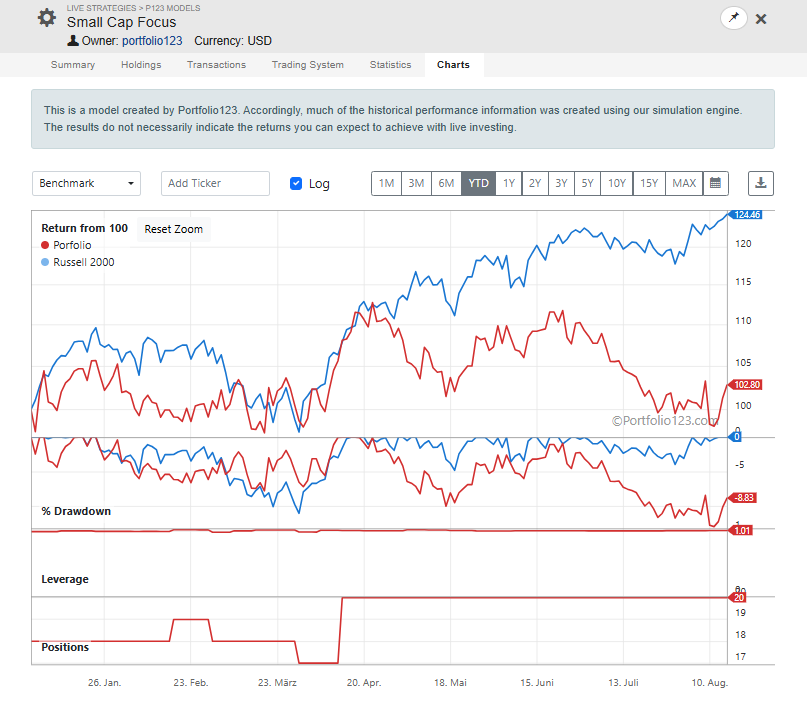
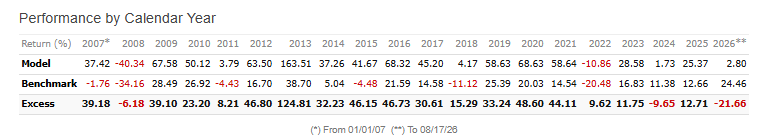
I started researching some tweaks in AIFactor to make the universe work. It is not even that restrictive. I removes the largest 25% of stocks by market cap (leaving you with stocks somewhere below $1.5B $2B mcap as of today) and applies some liquidity filters leaving you with >1000 stocks consistently. The “best” AIFactor tweaks I found had a great Q1/Q2 but still show the recent collapse.

My ExUS strategies are doing great YTD, so it seems to be a pure US problem. Also all of the classic factor strategies that work YTD in my microcap universe (such as pure value, or value-centric multifactor etc.) are actually just playing catch-up and lagged long-term + in recent history. You can see the same trend between the 2 small & microcap focus versions:
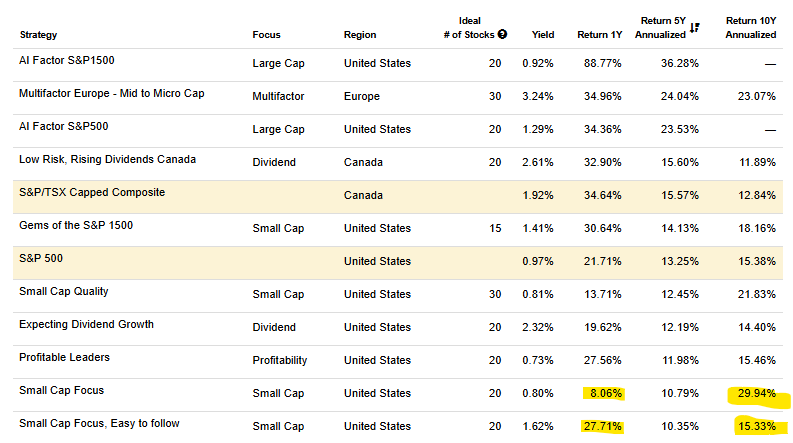
Would love to hear from the US-only smicrocap gang if you see the same thing this year. What do you think is going on here?
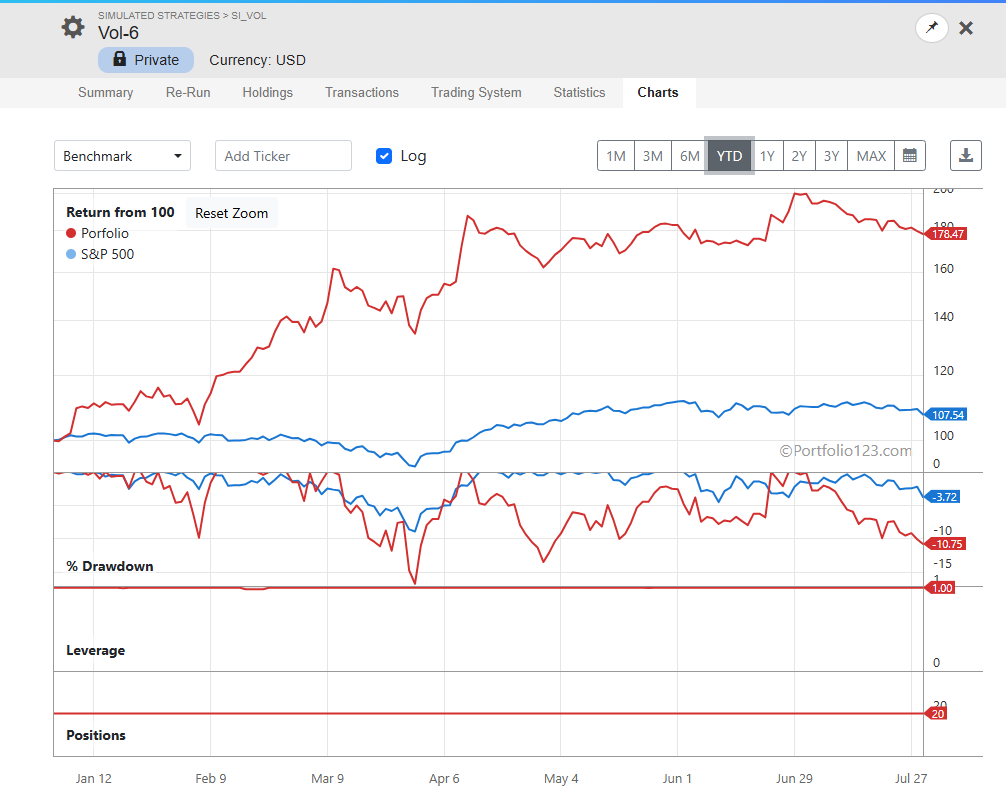
Yes, I’ve noticed the same thing. Since around the beginning of June, roughly 90% of my U.S. micro-cap strategies have been in a drawdown. They only started to recover slightly last week.

I’m using AIFactor with a large and diverse set of features across different factor families, 20 stocks small and micro universe


Hmm. I haven't been having that problem. I run three North America only long-only strategies, mostly microcaps and small caps. Here are the YTD returns:


Hi!

I'd need to know a few more details to give reliable advice. But here are some “off-the-cuff” tips that might be helpful:

  • I'm not a big fan of having fluctuating positions in the portfolio. Perhaps the buy rules or the universe rules are too restrictive. For the AI Factor, you generally want a universe of significant size and to give it enough “room to breathe” so it can perform optimally.

  • I see that with such a low turnover, it might be highly dependent on the initial rotation, but this is just a guess...

  • Your portfolio has been decimated by the momentum and high-beta reversal. Be careful not to give these two factors excessive weight in the portfolio. The backtest will always look spectacular, but in live trading, it can be a game of chance.

  • I would consider adding SecCount or SecWeight constraints to your strat, as well as position size constraints. I’m a really big fan of having between 20-30 stocks per strategy. That way I’m more or less sure that the stock-specific risk doesn’t drive all the performance in the backtest.

That’s all I can offer… I hope this has been helpful.

how many of the stocks are Canadian?

Current holdings: in the first strategy, 1 out of 22; in the second, 2 out of 22; in the third, either 4 or 6 out of 44 depending on whether you count double-listed companies like MAKO and OGC or not.

Any thoughts as to why the P123 Small Cap Focus is lagging so much this year? I realize that is only 20 positions, but it seems to be lagging unusually this YTD period.

That’s my main question. What separates a working 2026 US small&microcap strategy (feels like that’s every P123 user but me :grinning_face_with_smiling_eyes: ) from a failing one (US microcap universe + Core Combination, Small & Mircocap Focus, etc.)
That’s my main question. What separates a working 2026 US small&microcap strategy (feels like that’s every P123 user but me :grinning_face_with_smiling_eyes: ) from a failing one (US microcap universe + Core Combination, Small & Mircocap Focus, etc.)
This my strategy if I add two simple buy rules:

FCFq <0
EPSExclXorQ < 0

(lol)

But that’s also not the only answer. Some screens and strategies with explicite profitability rules, like “Tiny Titans”, are killing it YTD. This year is such a mess…

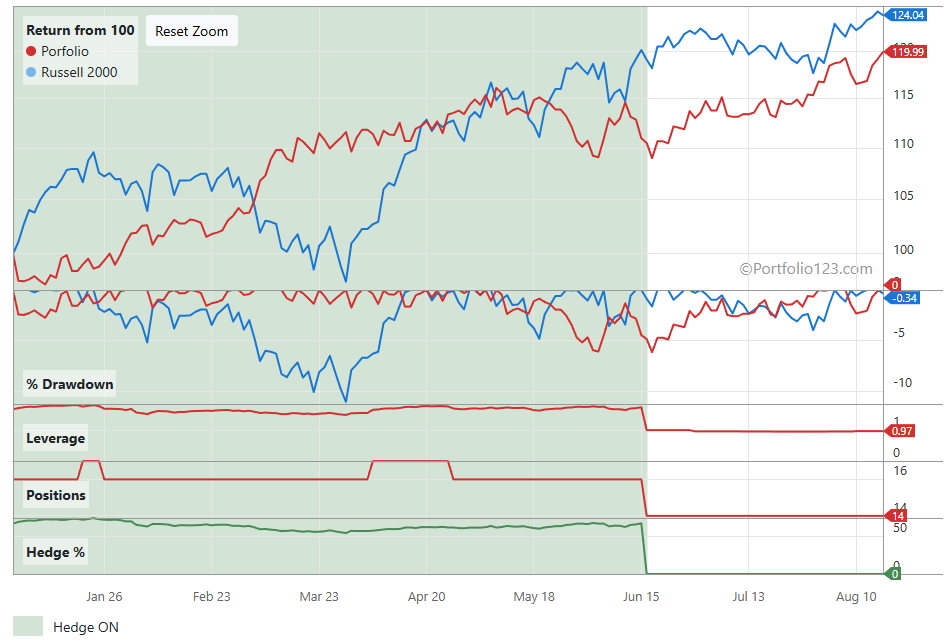
I only trade one pure US Microcap AI strategy which actually has been one of the better performers this year (the short ETF hedges have hurt overall performance , I moved the hedges into a dedicated book hence the green/white shading in the chart ).

The only Buy rules I apply are

IndCount < X

StaleStmt = 0

PendingCorpAct ( #MANDA) = FALSE

SubIndCount < Y

X&Y are relatively small compared to the number of positions.

No, I don't know. Most of the holdings are in my own portfolios too.

Sorry. So are you saying your YTD performance posted above is all driven by positions outside the Small Cap Focus port despite holding many of the same underperforming positions in common?

I haven't done a detailed comparison of my past positions with those of Small Cap Focus. I think the stocks that made me the most money this year in those strategies posted above are ANIK, AUGO, BUKS, EDRY, GLBS, INNV, OESX, OOMA, OPHC, SIF, and TRX (in alphabetical order).

Ah - microcap quant investing - volatility is one thing on paper, another in real life ;-).

All strats below are traditional ranking, weekly rebal, 20-25 positions. (AI strategies under development)

My US microcap strategies had a rough 2025 - my “flagship” GUTS-Y system for US just barely stayed above water, while IWC and others were on a tear. 2026 it’s done better, but still lagging IWC. I’ve recently been deconstructing my strategies to see if I can see what types of microcaps each tends to favour (more specific than just value/growth etc, but what kind of growth, and value etc). GUTS-Y tends to be more conservative, likes FCF (which can be a good or a bad thing, depending on the market regime). But also I found the timing was off - it was catching a lot of stocks near their peaks - and some deep sell-offs after earnings (beat or miss). 2025 was painful.

For comparison, my GUTS-J is my other US system, has done slightly better, but underperformed in 2025, now outperforming GUTS-Y in 2026.

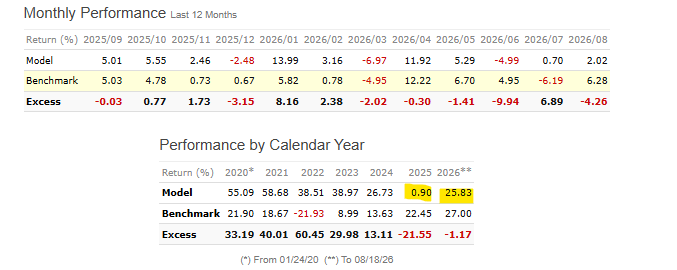
Another point - regardless of US or Canada, Europe etc - start date can make a significant difference. i.e. one of my Canadian GUTS strategies, I’ve been running live since 2020. Has struggled in 2026 (gold exposure) - first snip. But exactly the same strategy - ranking, universe, rules - I took and started a separate account last year on new capital. It selected fresh new holdings, some different than the 2020 portfolio. But it’s performed quite differently YTD (second snip):

All of our strats are different, but perhaps some points above can shed some light.

Cheers,

Ryan

I am seeing the same things you are describing for 2025 here in 2026 for my strategies. Most losses this year come from bad entries (buying into failed breakouts or shortly before an earnings miss). Changes to the simulation which affect timing of trades (such as rank tolerance) has a big effect on YTD outcome. Another predictor I trained now for research purposes buys many of the same stocks but with much better timing.

In long-term sims, sometimes you can't even spot the difference. Is 2025/2026 just much more prone to timing luck?

For example: My microcap universe + Core Combination

Quarterly rebalance, RankPos > 50 starting 01/01/26:

Weekly rebalance, RankPos > 50 (100 looks the same) starting 01/01/26:

Not sure what it's worth, but the hardest part of model evaluation for me is discerning "edge" from "overfit" — or from plain timing luck — since all three can seemingly describe the same model at different points in a return stream. I'm not sure the sample sizes we're dealing with can distinguish among those conditions.

Acknowledging that some models may be overfit, the question becomes: is that necessarily bad in a portfolio context? My lingering question is always: am I better off with many models (accepting some may be overfit) and betting that the diversification benefit outweighs the concern? Or am I better off relying on the simplest version of things I trust most to do fairly well most consistently? Those models, perhaps with fewer peaks recently, seem to be churning along just fine.

Part of the answer is that there are two versions of myself — the trader and the version who wants to autopilot attractive returns with a reasonable volatility profile. The latter is the one I say I want to be, and as I've gotten older, when I'm drawn back to the tendencies of the former (which is actively happening a lot, even right now), I've tried to remind myself to step back. Easier said than done, as some of you I've communicated with recently have seen!

I am biased because I do the former (4 concentrated strats in a book; more to come when APAC is out) vs. a simple "all-in-one model" I have for friends and family but:

Building several strategies with theoretical (possibly overfitted) high EV but different universes, core signals, regions, industries, turnover etc. etc. and low correlation is the safer way to go in my opinion. If you rebalance those frequently, you can "harvest" some of the substrategy volatility. It is possible to express this in one big universal model (strategy) but to account for all the diversification needs, you have to take too many compromises.

If I really had to trade ONE model, it would be my all-in-one North Atlantic strategy with higher number of positions. But I am 90% certain, that the diversified book of concentrated (specialized strategies) is superior long-term.

I sometimes miss the version of myself that quite possibly would have been wondering what to do with a 130% gain in Moderna this morning : )

I'm a bit confused by what you mean by rebalancing. Are you rebalancing within strategies for each geographic location? And then you're also rebalancing between U.S., Canada, Europe, etc., right? How often are you rebalancing?

I "rebalance" only the cash amounts weekly. I work completely in live strategies and do my trades manually (I later edit the transaction data to the actual real transaction costs in IBKR).

I use P123 Accounts (Manage) and Live Books only for tracking and visuals.

Once a week I check the capital in each strategy and even it out by adding manual cash transactions. That results in negative cash in recent winner strats and free new cash in a loser strat.

Ideally all strategies have rebalance transactions planned. If not and if the cash deviation is too big ("leverage" <0.95 or > 1.05) I either add a new best position to be fully invested or sell the worst-ranked one to raise cash. So you will be slightly off-target regarding number of positions, but if that should break your strategy, you have other problems.

I do not rebalance by selling/buying shares of every open position. I hate such transactions that bloat the order book.

Tldr:

I rebalance on book level but I only reconstitute on strategy level.