Yuval. Why do you prefer SubSecCount<x as opposed to SectorCount<x?
I don't mind having 50% of my portfolio in one sector, but I prefer not to have too much of my portfolio in one subsector. Correlations of stocks within a sector are quite a bit lower than in a subsector.
Does force stocks into universe, push finance, utilities and REITS back into the universe?
I’m using RBICS(302520)=0, RBICS(65)=0 and RBICS(30)=0, and still getting Financials in my simulation.
Also, love your work Kurtis. Been really appreciating your videos as I’ve started the P123 journey.
It shouldn’t. Because it won’t get bought in the first place. It will only keep existing portfolio positions in the universe.
The only thing I can think of is maybe FactSet reclassified a stock. It entered as a different sector, you bought it, and it was reclassified as a financial stock.
To test this, put sell rules in your simulation as well such as RBICS(30)=1. That way if this happens it will kick it out of your portfolio and not allow it back in (hopefully).
Also, just brainstorming here: if a buy rule is highly cyclical or too dependent on the market regime, should it even be a buy rule at all (assuming it doesn't belong in the universe either)? Wouldn’t its proper place be in the ranking system instead?
Or have an Eval function
Using Eval could be a solution, but you would still need a trigger to identify cyclicality or the market regime. At least for me, it would be very hard to define.
Pickup up this old thread to ask again: Curious what everyone uses as your default universe
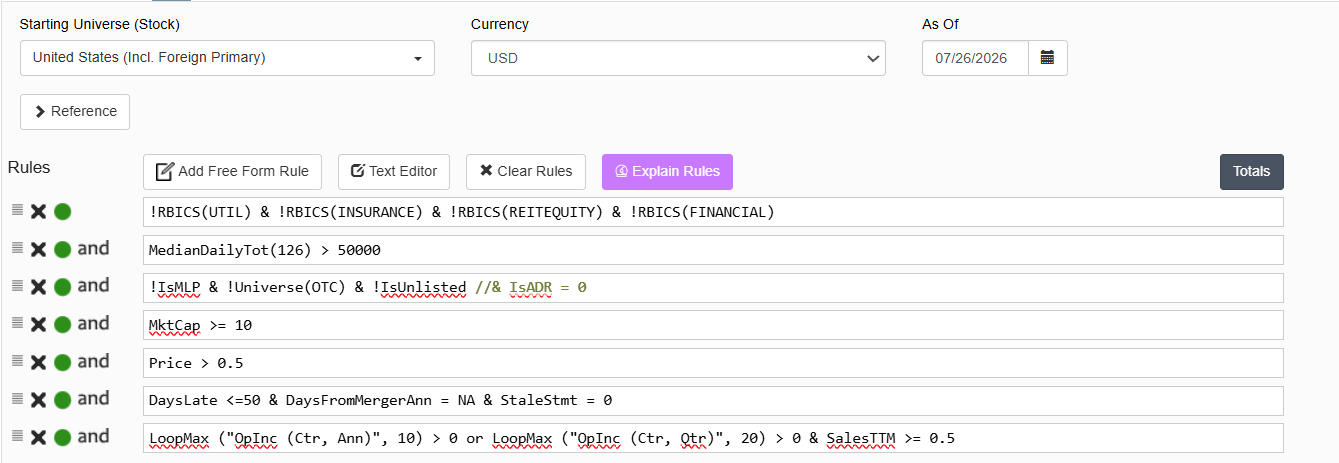
- How many stocks are a part of your default universe my screen print above provides 2400 stocks… is that enough/not enough?
- Why you think that is a good idea for your number of stocks in the universe?
- Why you did or did not exclude certain rules in your universe?
- Starting universe: North Atlantic.
- A formula excluding stocks likely to have committed fraud or manipulated earnings; excludes 3% of stocks in universe.
- A formula excluding stocks that have paid exceptionally large special dividends since the last announcement, since this distorts practically all fundamentals.
- A formula excluding stocks with merger activity.
- Market cap greater than $10M and median daily dollar volume greater than $5,000.
- Exclude stocks trading in exchanges which my broker doesn't deal with.
- Exclude stocks that haven't had any positive operating income in the last twenty quarters.
- Exclude stocks with a FactSet mismatch between the latest interim and latest annual periods.
This is for screening stocks for immediate buys.
For backtesting I add three additional screening rules:
- Exclude stocks whose market cap has never been greater than $20M.
- Exclude stocks with stale statements.
- Exclude stocks with such large transaction costs that I wouldn't buy them even if they passed the above screen.
The universe definition is based on the NOOTC universe.
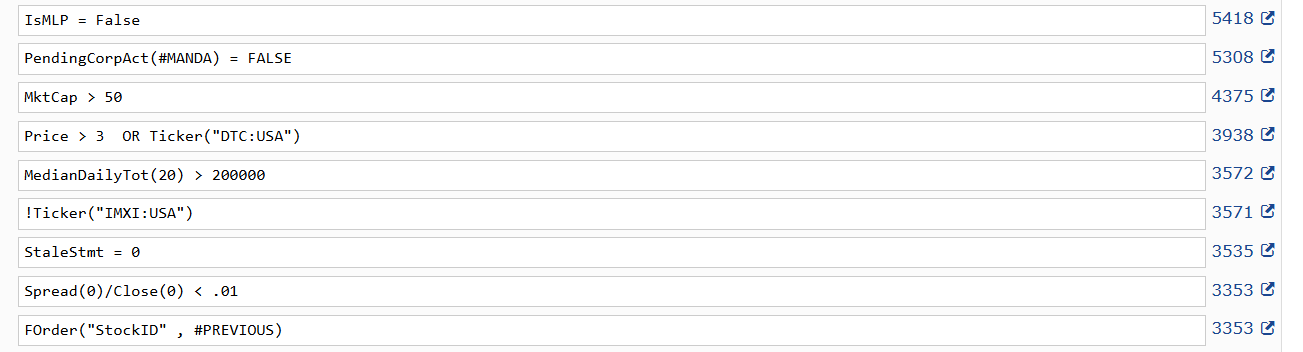
The screens I run have very high turnover which I compensate for by demanding more liquidity. The count of 3353 names is around the median. In hot markets it can get to 3600+ and in cold markets it has been below 3000.
While the minimum market cap is $50 million, the actual owned market cap tends to be above $150 million.
The other universe I use adds in “Between(WeeksIntoQ, 0, 14) = TRUE” which can make a significant difference on some screens.
Cheers,
Rich