We all know that since July 1, 2026, the markets have been downright strange. Everything that worked in the past has temporarily stopped working. Instead of trying to predict the future, we should analyze the past and the present.
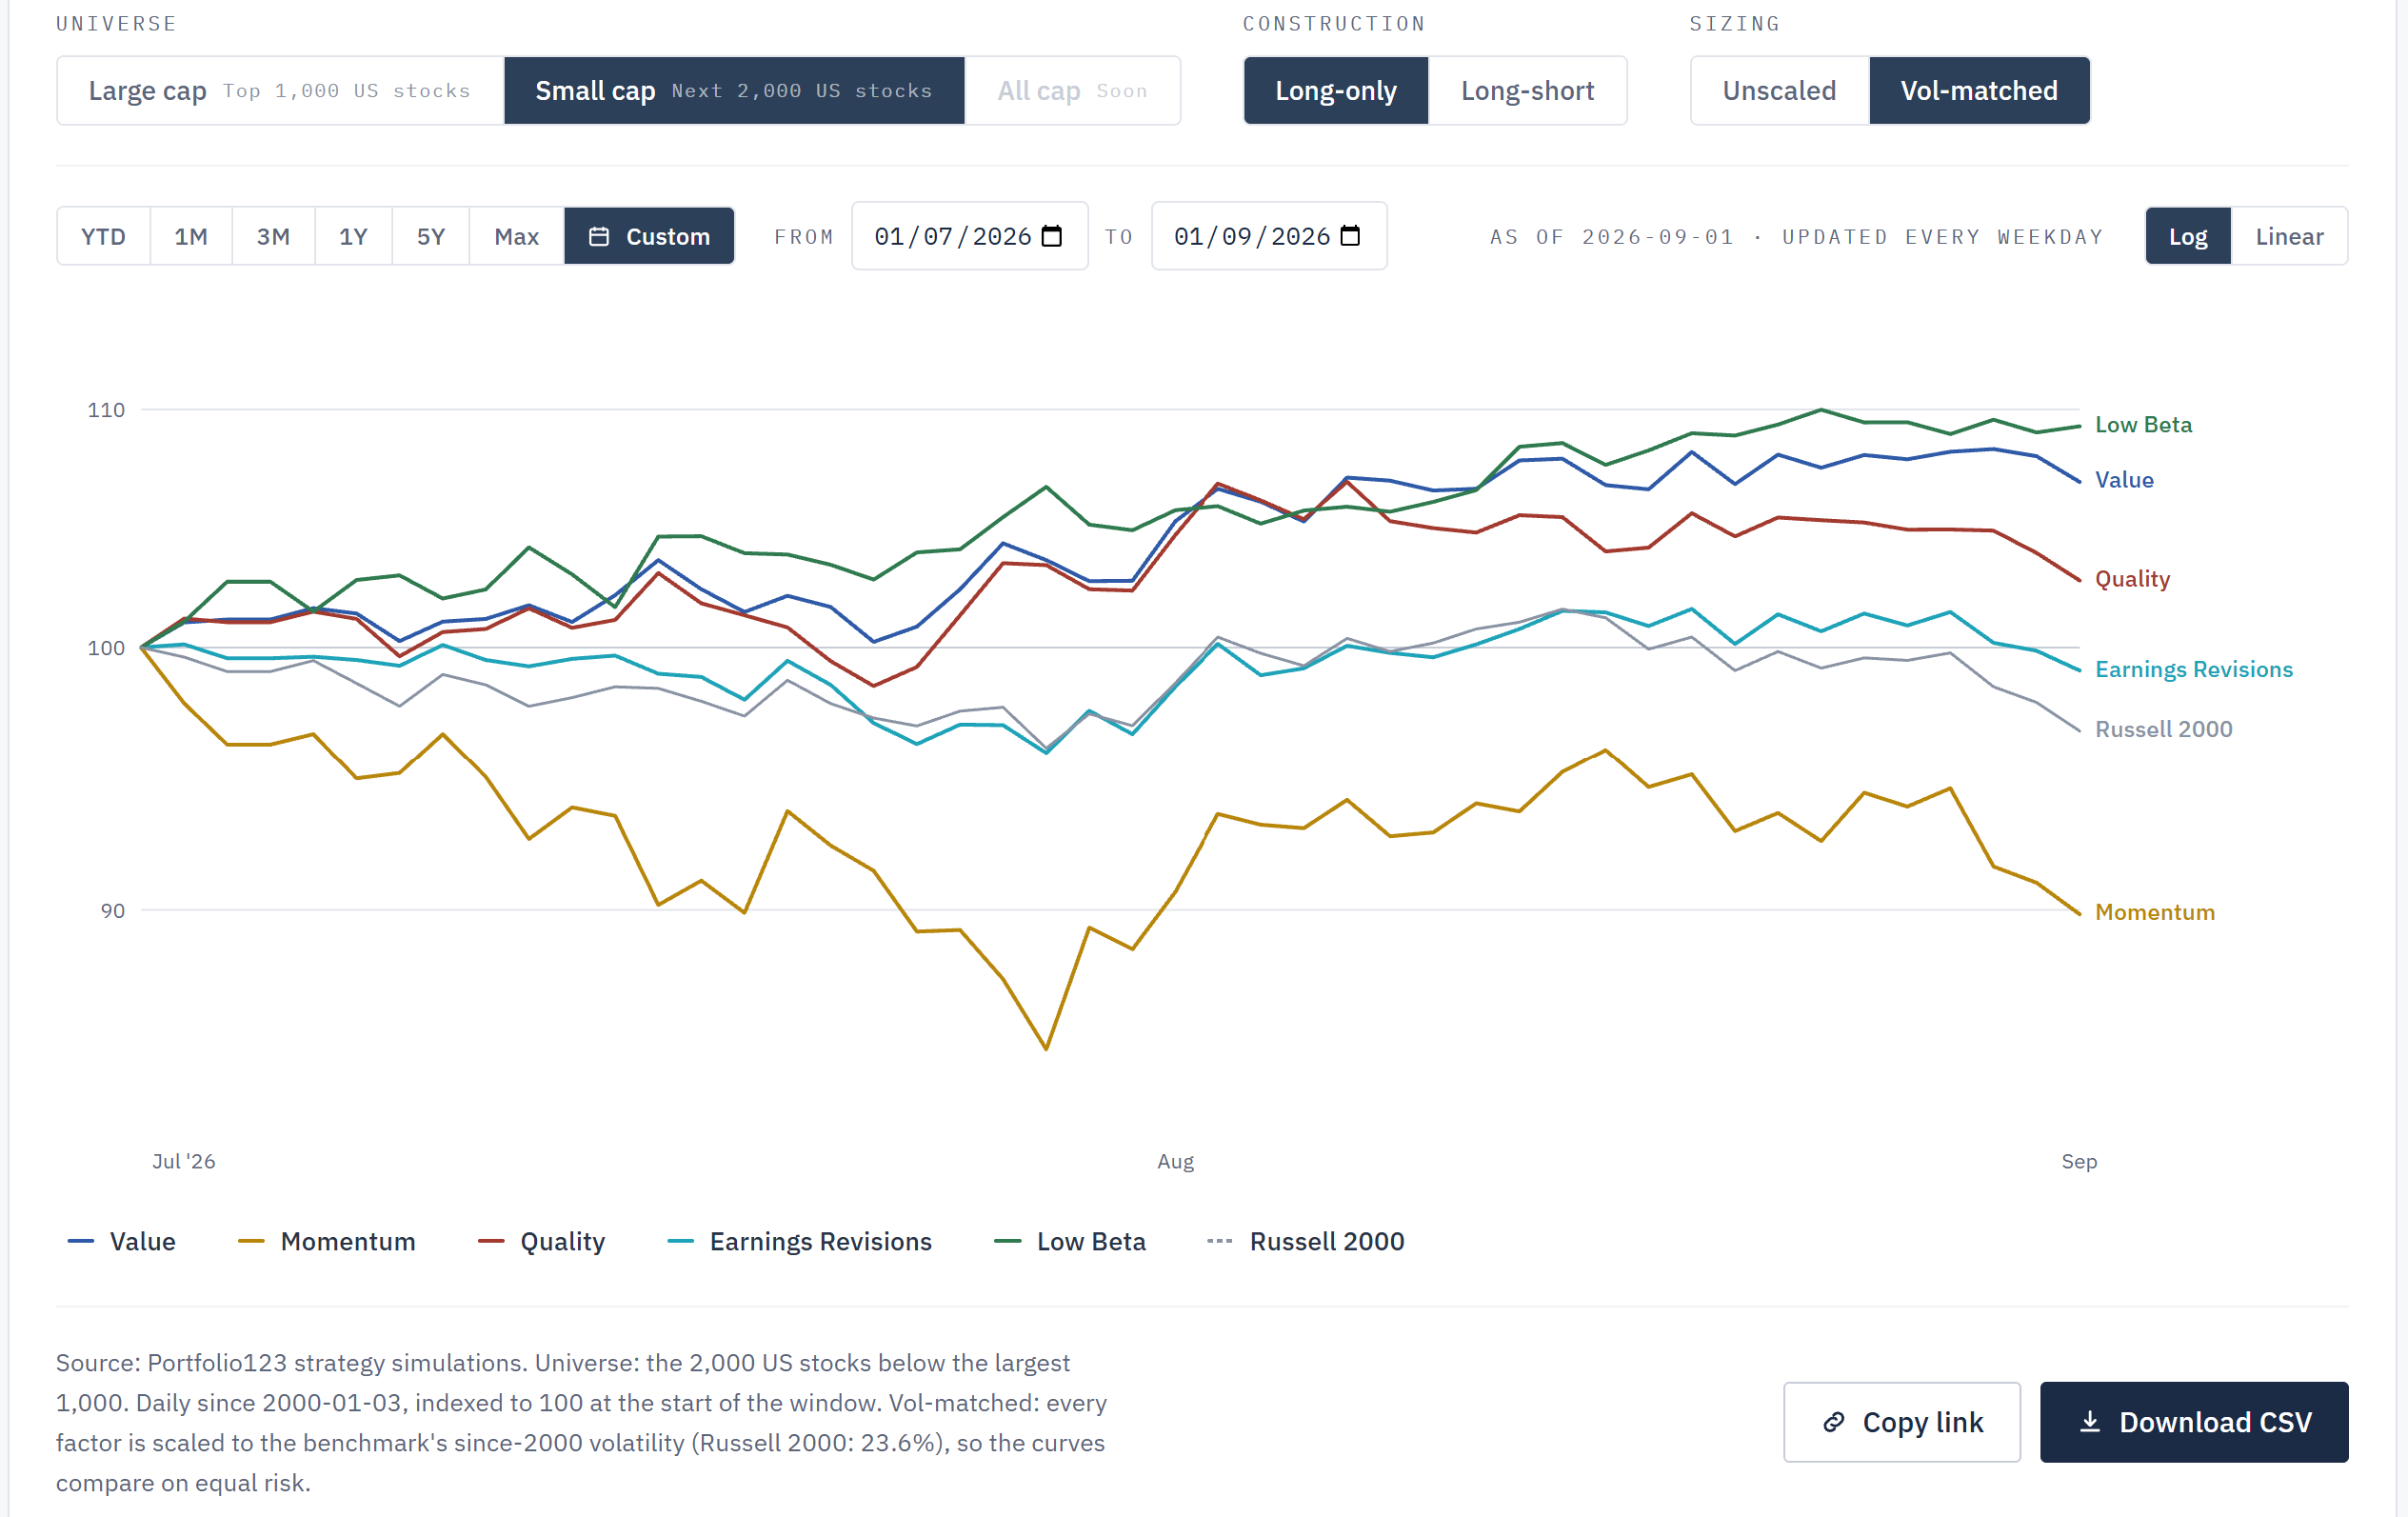
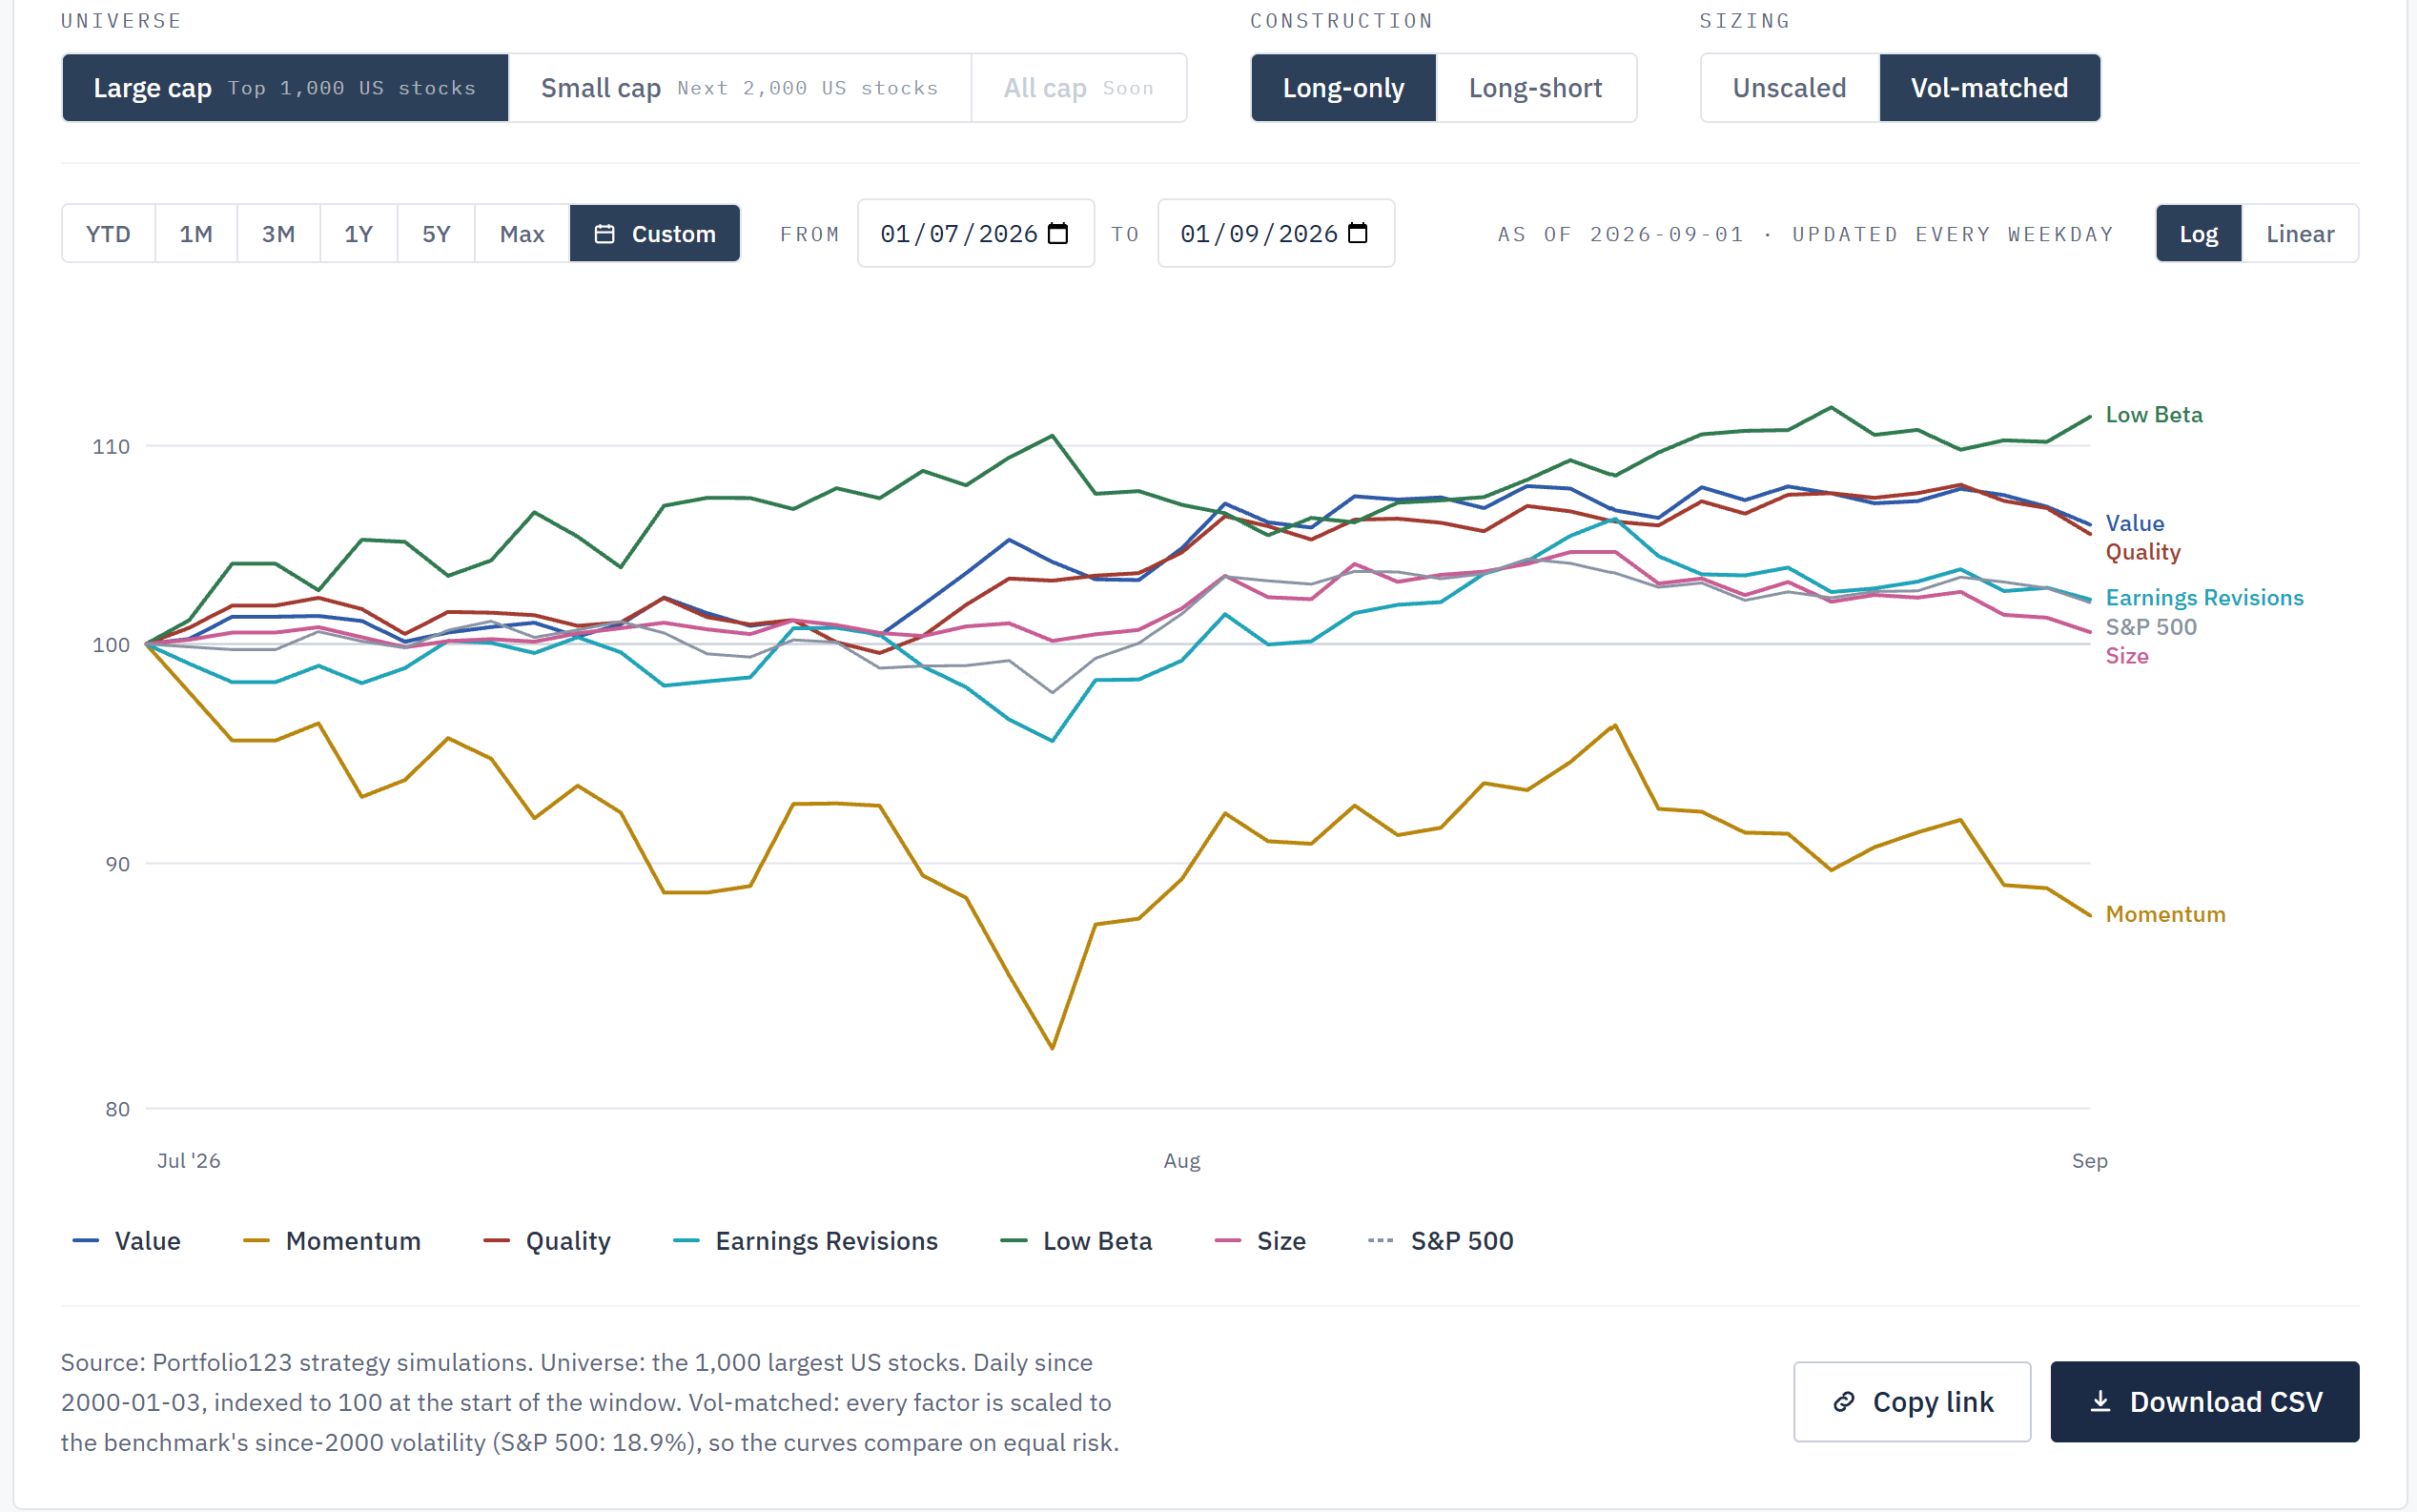
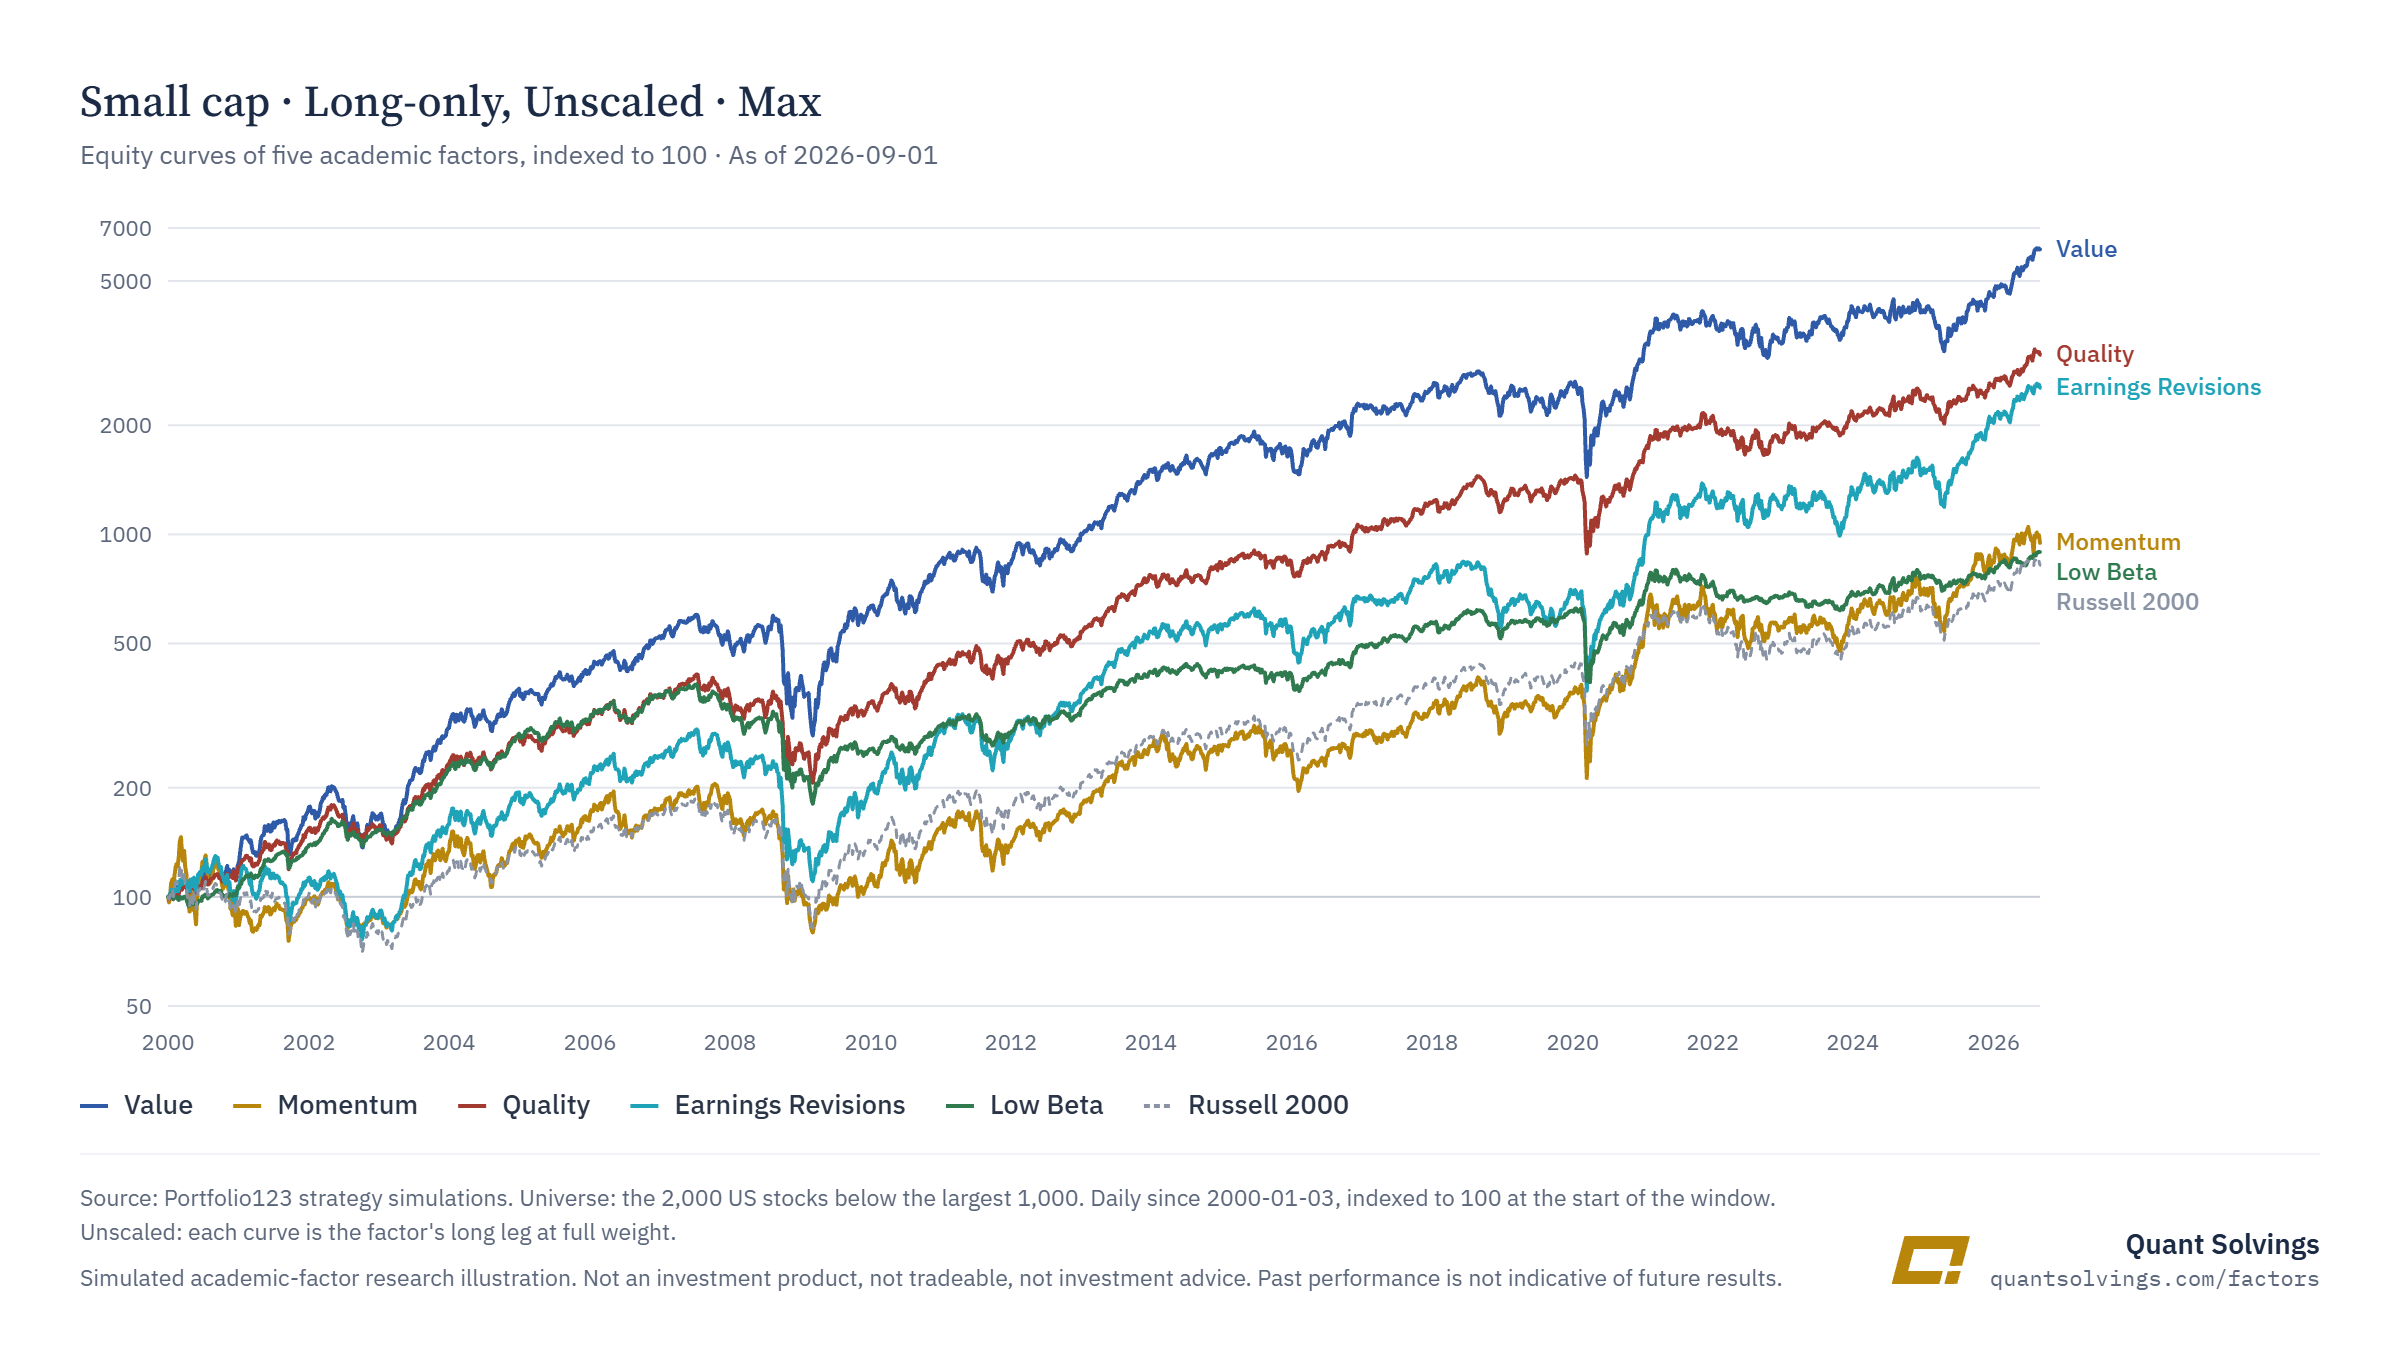
Here are some charts showing the “vol-matched” performance of traditional factors in both large-cap and small-cap stocks:
You don't have to be a genius to see that the “high-beta” and “high-momentum” stock bonanza is slowly coming to an end. But that's not the most interesting part...
We’ve seen a very recent acceleration in the low-beta factor over the last few days. That’s why I think it’s extremely important to make “vol-matched” comparisons, because sometimes we think a factor is the clear winner when it’s literally just pure beta.
Keep an eye on your portfolios!! What do you guys think?
I can mimmick the fail vs. success split in my recent US microcap (junk) performance either by incl./excl. High-Beta but also 1:1 by incl./excl. High-Debt/Assets (D/A > 0.5).
Latter explanation makes much more intuitive sense to me regarding the recent global yield tandrum. Of course high beta is highly correlated to this.
Was a blindspot of mine. But even after this drop, playing the junk game in "true" US microcap (no foreign headquarter) seems to be the better diversifier long-term in my book. So I will stay the course. It's a volatile ML gamble. Would never dare to buy ExUS junk. Global ML predictors tend to agree and avoid junk like a plague overseas. In US, sinning a little can pay off (even though it clearly didn't for me recently)
It may be true that, even within a sector that is underperforming, we can find some “crown jewels.” Furthermore, this would also align with a “contrarian” investment style.
However, having that kind of exposure can be very risky. Let me explain: If, out of 200 companies in a factor, there’s only a subset of 40 that are performing quite well, your odds are already very low. Typically, these types of strategies rely on capitalizing on the asymmetry of their winners. So, if they manage to find a winner, they increase the position’s weight to get the most out of the stock. Even so, this increases the portfolio’s stock-specific risk and leads to very high volatility.
That’s why I always emphasize making “vol-matched” comparisons of our strategies. Often, those returns can be explained by excessive exposure to one or two stocks that have performed very well in the past.
As you can see, I’m pretty conservative—I’d rather have high-probability “mini-wins” and control my portfolio’s risk than chase exponential gains. Maybe I really should learn to take a leap of faith every now and then, especially at my age! LOL.
What an odd observation. Everything that stopped working for me in the past is now working better than ever. In terms of excess returns, July and August were my best months since 2023.
Seems like there's a factor rotation underway towards value momentum and away from growth momentum. First appeared in November of last year, lasted till April as it took a bit of a breather with the explosive AI earnings season, seems to have resumed around June 1st and continuing. Open questions: a) whether this continues for longer (<1 year rotations can be short term noise), and b) if it does continue, is it a long term shift back into value from growth that has absolutely dominated since post-GFC?
Market seems to be concerned about sticky inflation above 2%, Fed rate hikes, bond market jitters due to the macro outlook + developed world fiscal profligacy. So, rotation in that context makes sense. Higher for longer means less money sloshing around to support growth momo.
The entire thing could reverse if there is a durable peace deal with Iran that sees the Bab al Mandeb and Hormuz straits fully open again -> oil falls sharply, gas and diesel drop. More cover for Warsh to cut instead of hike. Core CPI isn't that terrible, its mainly the energy shock driving inflation.