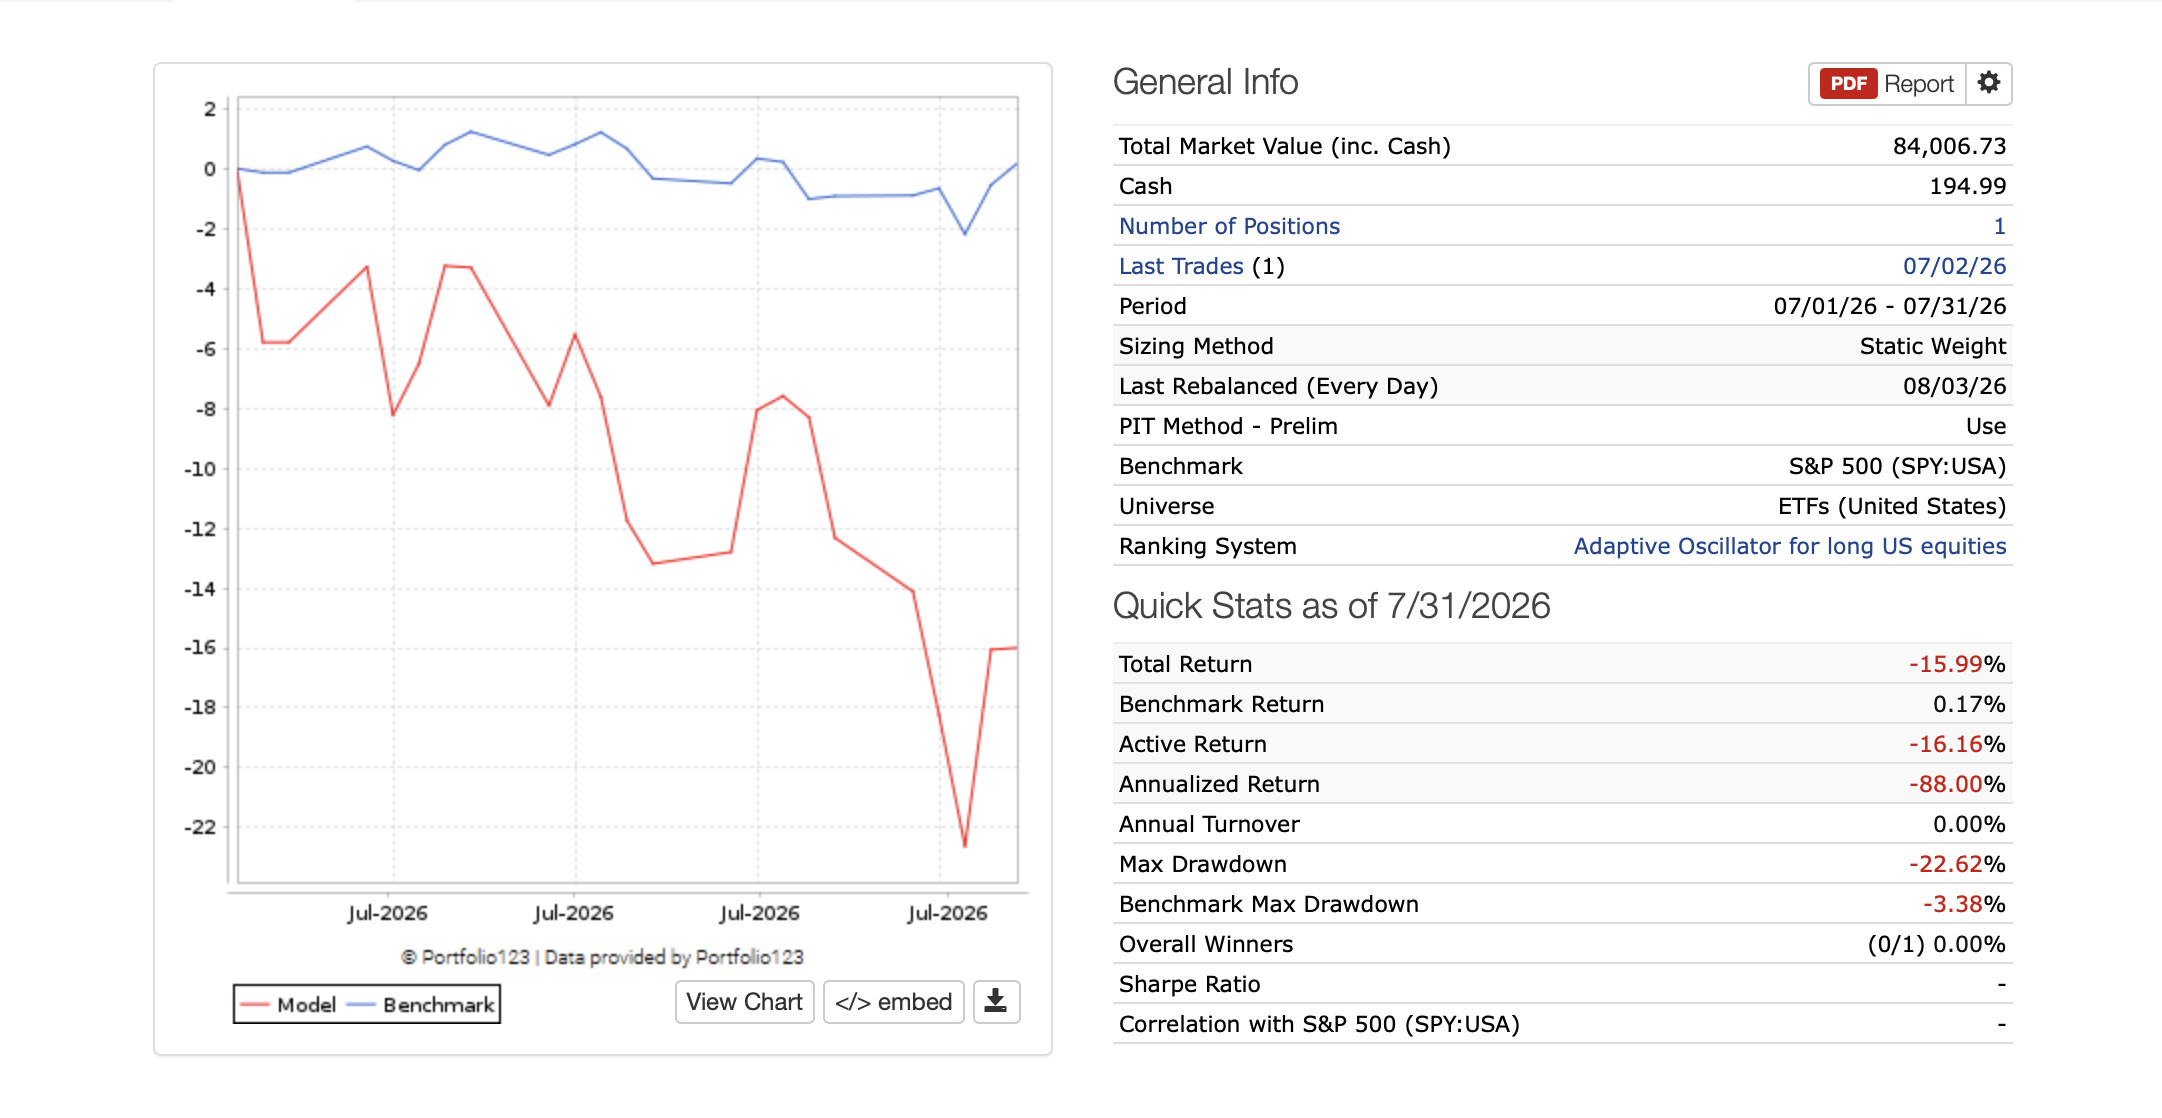
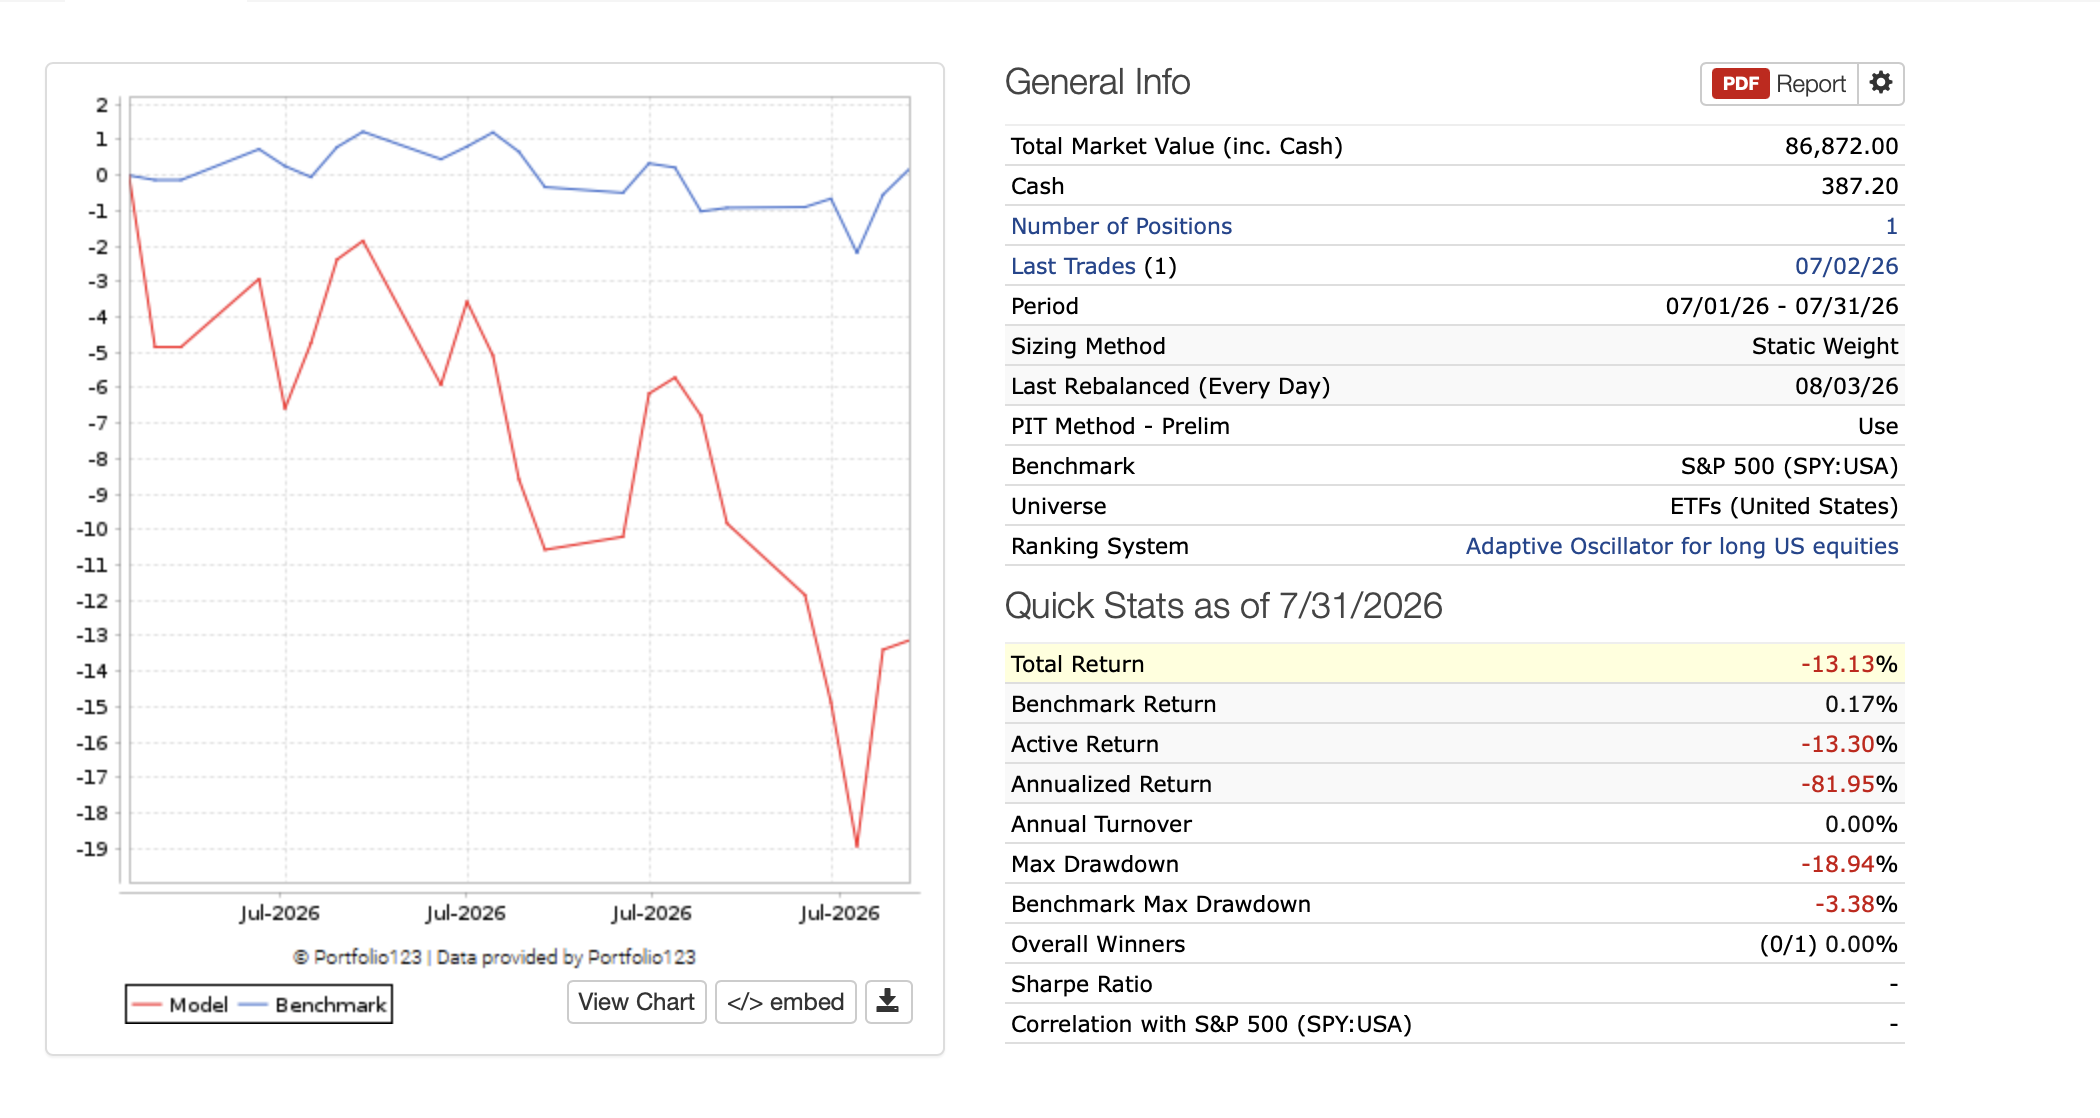
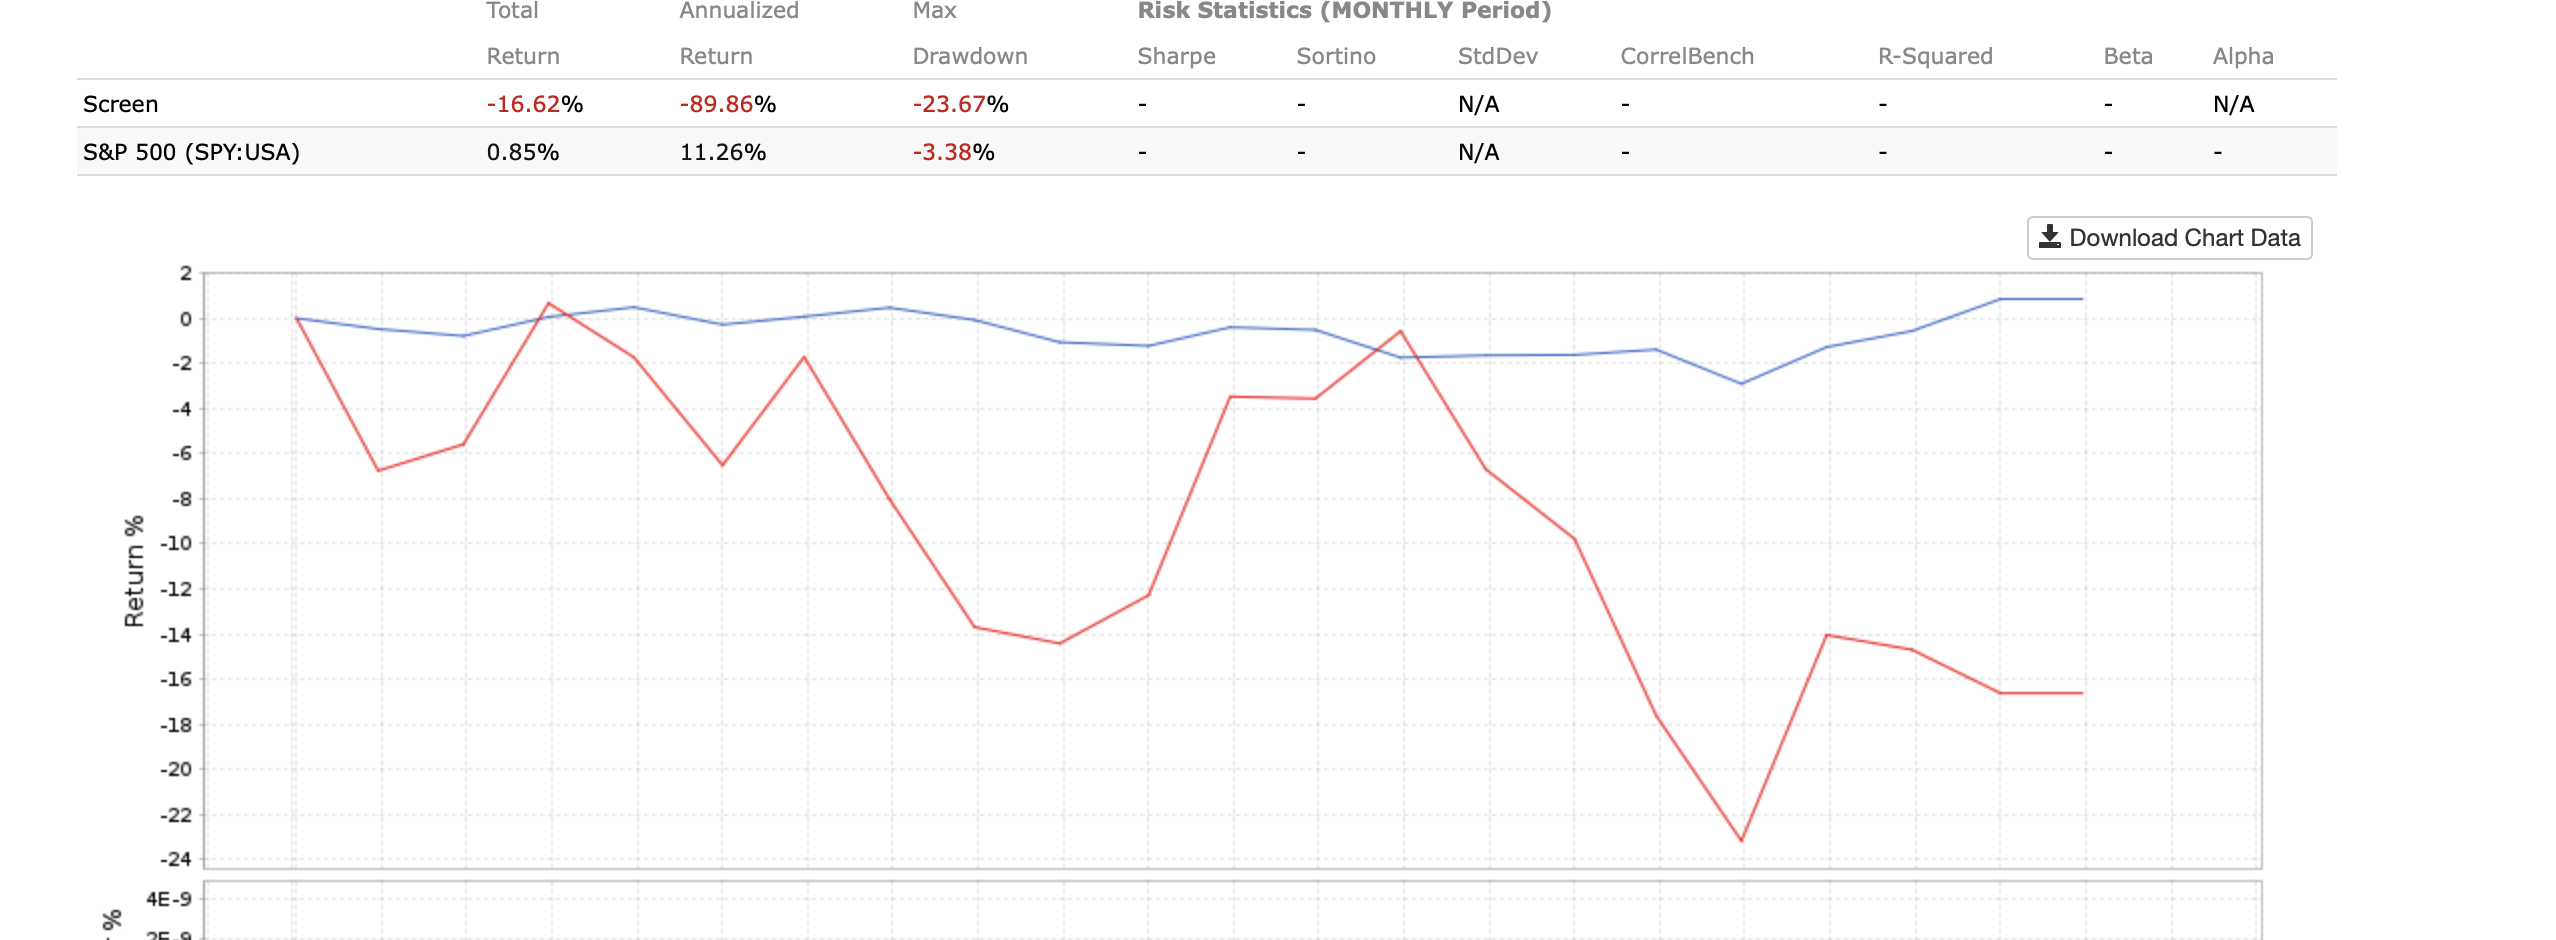
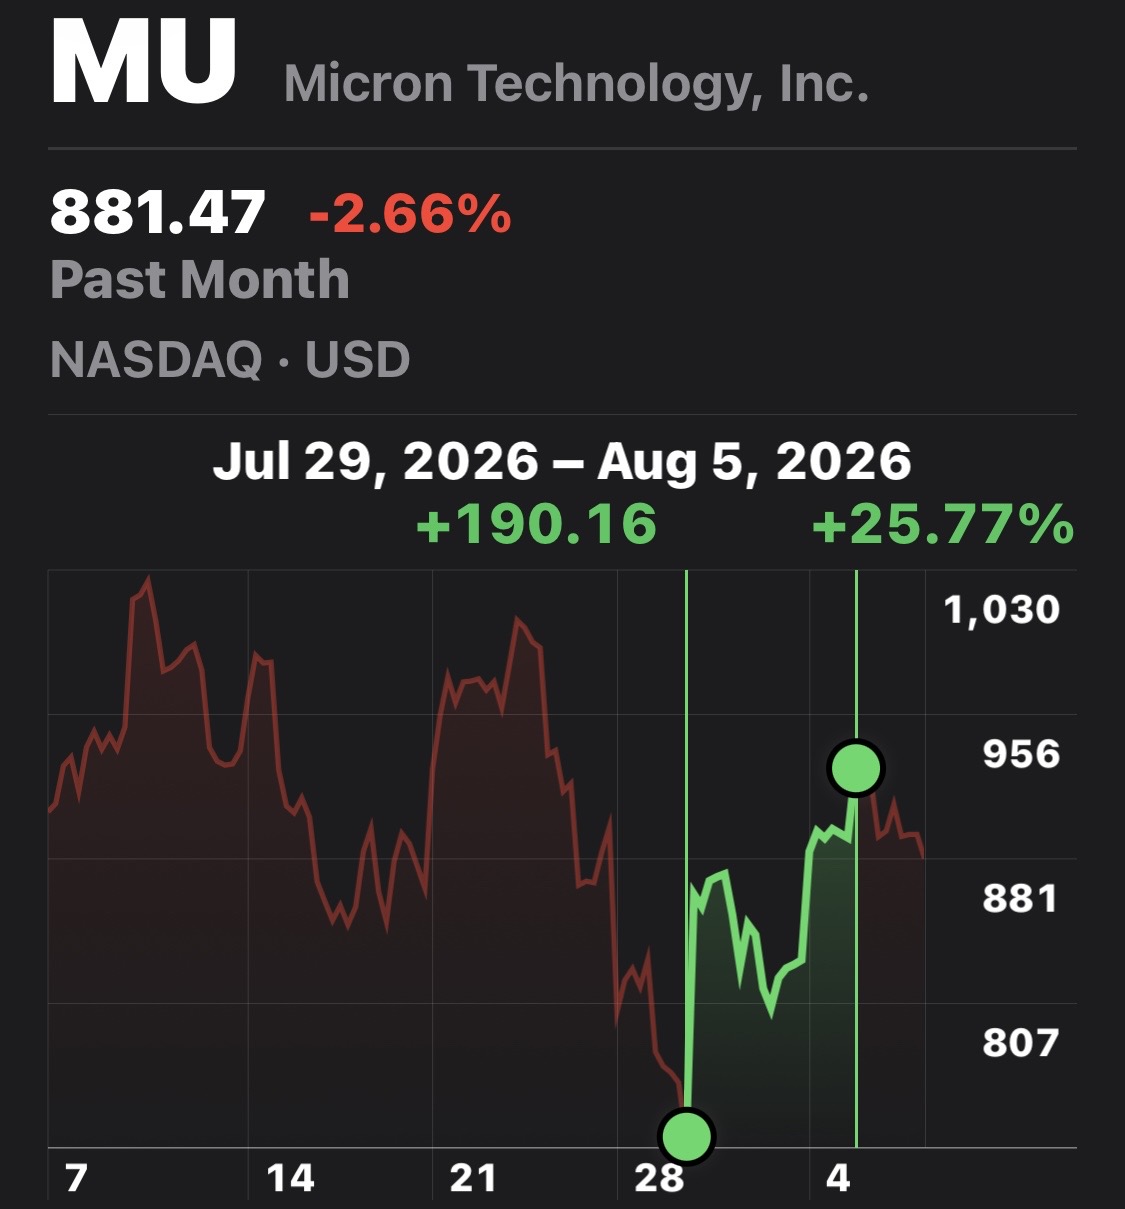
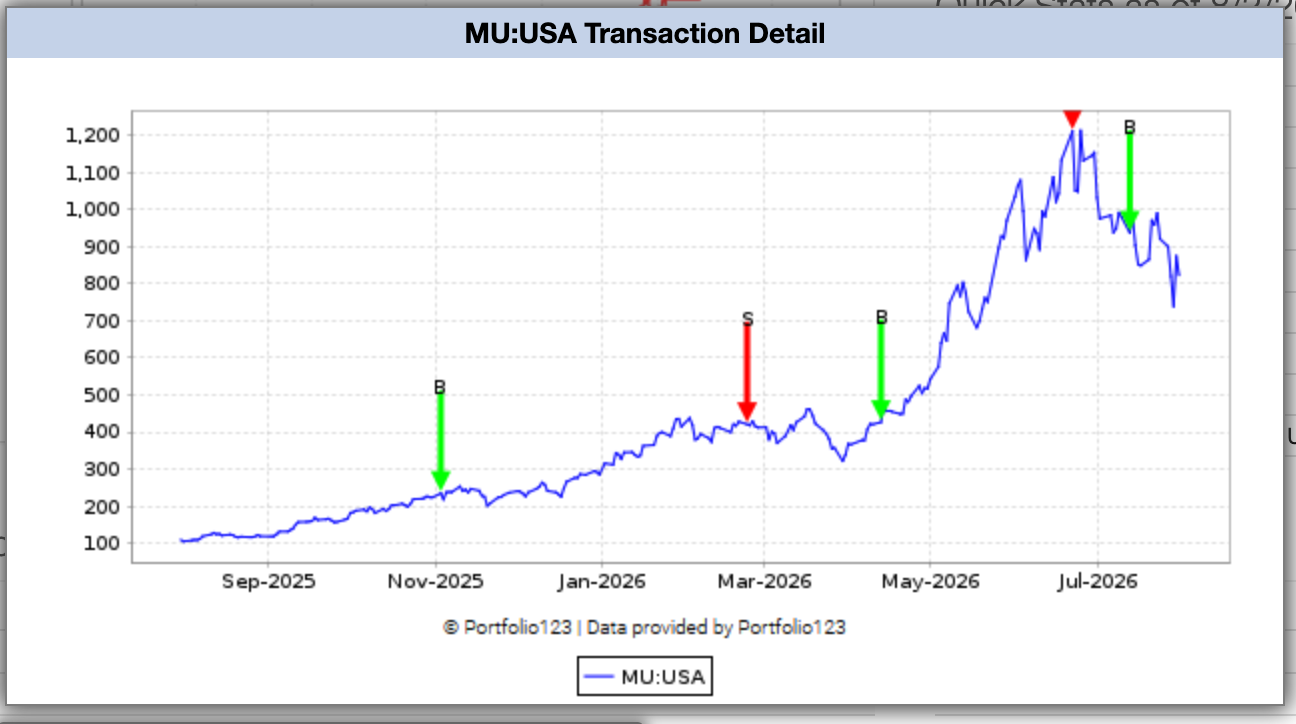
My large-cap strategy has invested in Micro Technologies (MU) three times in the last year, recording returns of 79.5% from Nov. 2025 to Feb. 2026, then 184% in two months, from April to June 2026. However, the model bought it again a couple of weeks ago, and since then it has continued in a selloff that has only accelerated.
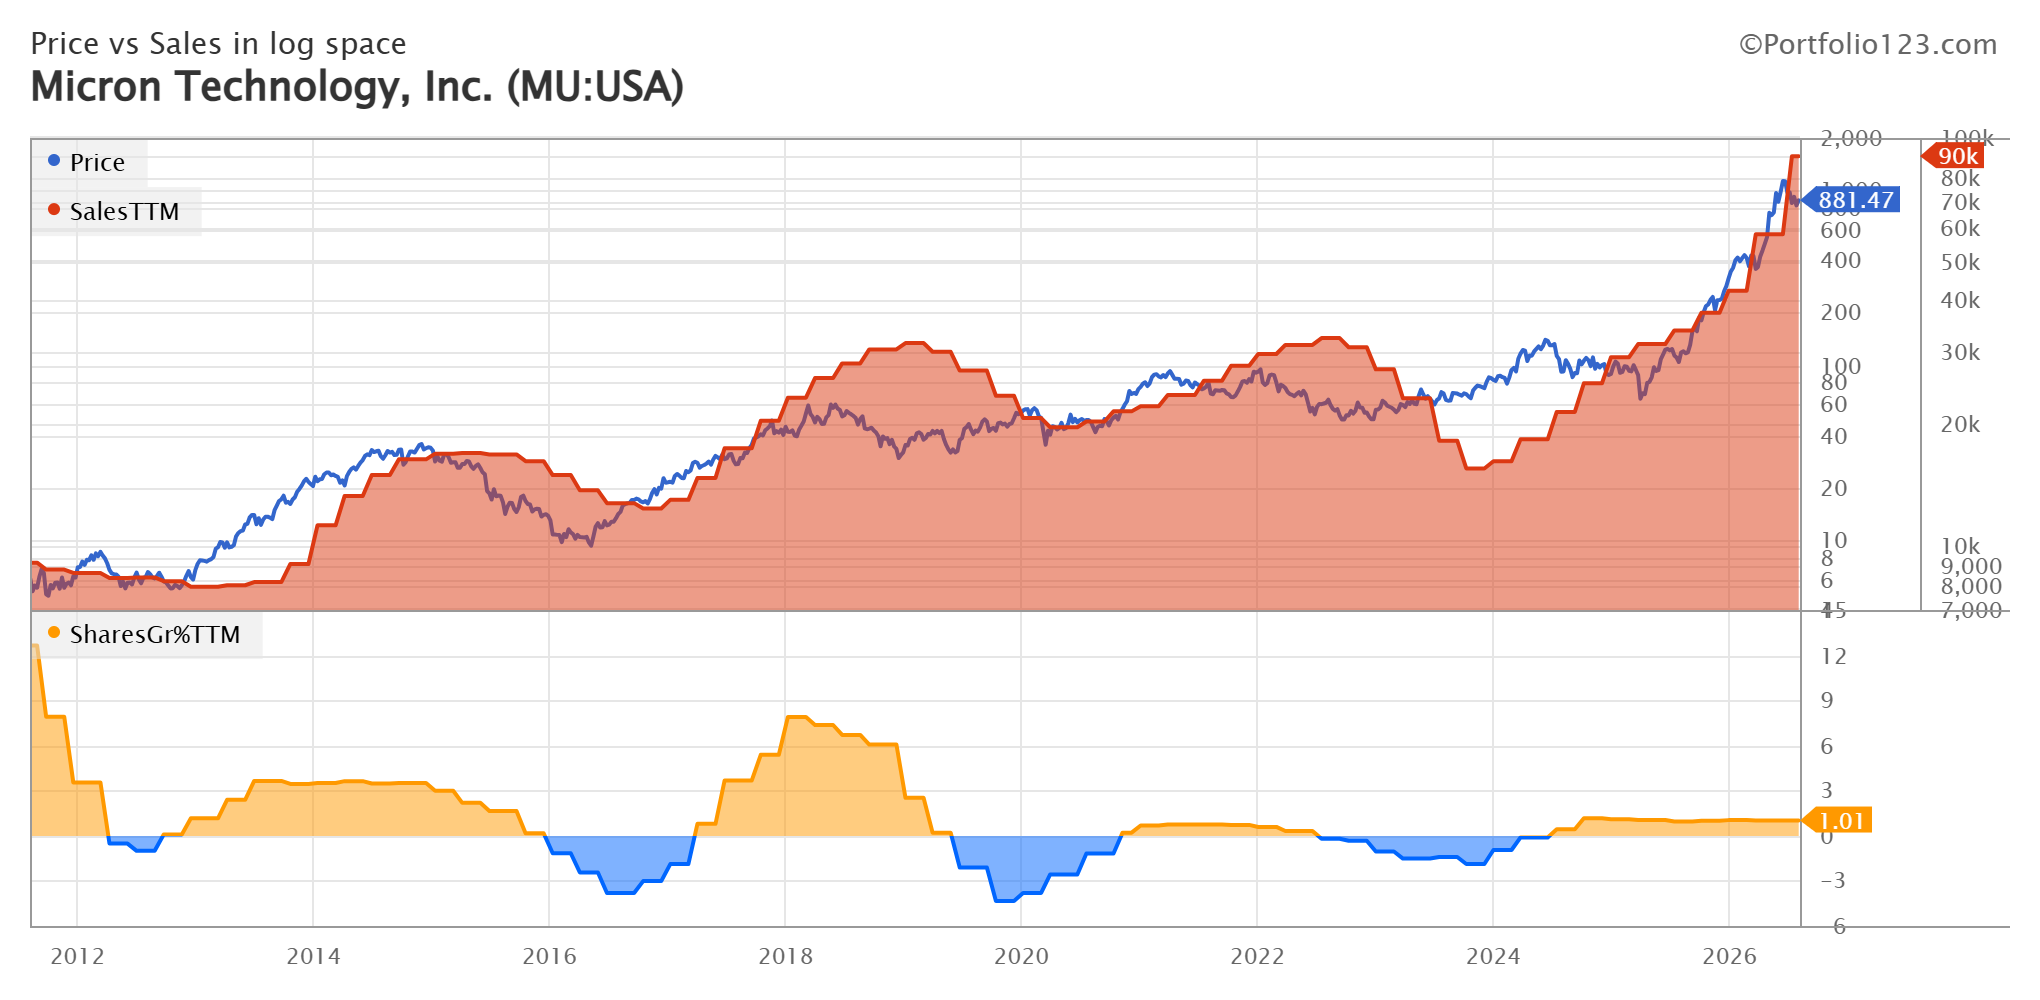
Micron is probably appearing on a lot of P123 screens and strategies these days because its fundamentals are phenomenal and it is considered undervalued by many measures. For example, it has:
• FQ3 (ended May 28) revenue of $41.4B, up 346% y/y. EPS of $24.67, up 1,368% y/y. Growth across all four segments, driven by HBM demand.
• Company guidance for the August quarter: about $50B revenue and $30.73 EPS.
• On TTM EPS of $44.23, that's a P/E near 18.6 versus roughly 32.6 for the Nasdaq-100. On the FY2027 consensus of $153.74, the forward P/E is about 5.3. That’s a forward PE of 5.3!!!
However, regardless of the incredible fundamentals of Micron and many other large-cap technology stocks (NVDA, LRCX, AMD, ARM, INTC, etc) fueled by the AI supercycle build-out, the market for that segment has been dramatically sinking based on sentiment alone since the late-June ATH. Mega-cap Tech is a verboten sector of the market, with individual losses of -30% to -70% since the end of June.
It was wonderful to score a 189% return in two months on MU, but now the chickens have come home for the entire AI-fueled segment of the market. There has been a significant rotation out of the semiconductor and memory suppliers selling to the incredible AI data-center buildout. Seems everyone is questioning the AI story now. Only time will tell…
I’ve tried adding some creative approaches in both the Buy and Sell rules to eliminate potential value-trap companies like Micron from getting in, but it resulted in lower CAGR and slightly higher MDD, accompanied by increased volatility. Apparently, these conditions don’t occur very often historically, so I’ve had poor luck trying to program out these value-trap stocks.
Curious whether anyone here handles semis with a sector-specific ranking system, or just accepts that generic value factors will periodically get run over by industry cycles. I've generally found trailing-earnings value needs a momentum or revision overlay to survive in this industry group, but this model has those factors built in from the start, to no avail.
Anyone have any favorite value-trap avoidance rules worth sharing? Thank you.