Hi all,
as many of you know since 2025 there are many stocks now available in tokenized form on various blockchains. These are trading 24/7 and make it an interesting experiment to exploit intraday price movements. I herewith briefly describe my approach and how I plan to generate alpha from it.
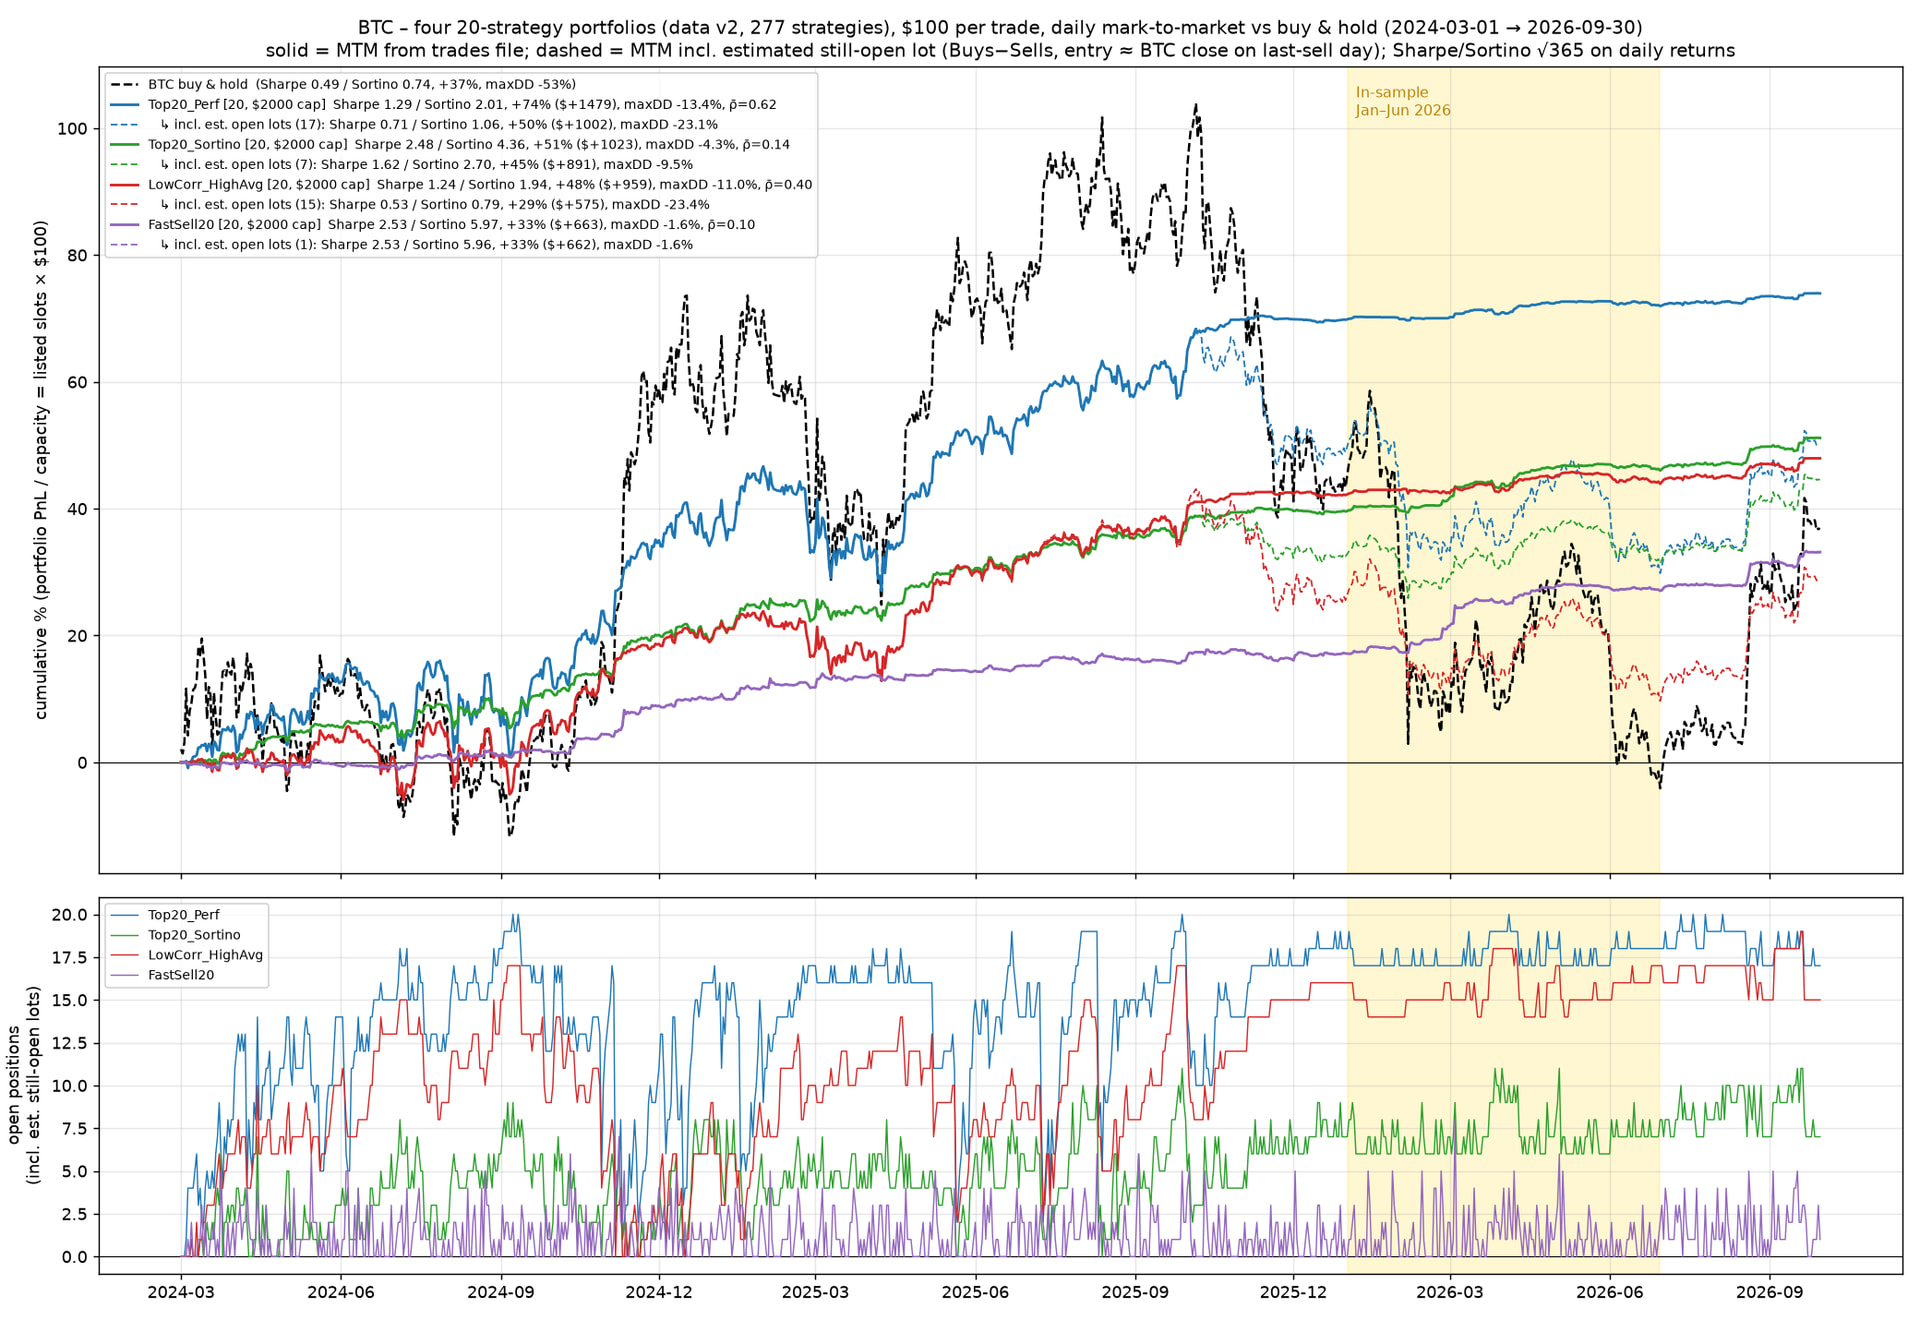
Initially the idea came from trading the main L1 crypto tokens BTC, ETH & SOL. To that extent I used the help of OpenClaw connected to Gemini 3.1 pro to code over 200 trading strategies based on 70 text books. Then I let OpenClaw fetch 1 minute candles from Binance and backtest the strategies over a 5 month period. I then used Grok bot to improve the strategies and finally backtested them against an out-of-sample dataset spanning 2 years (almost 1,000,000 1 minute candles per crypto token). Strategies were designed so they don't generate more than 10-20 trades per months even though they look at 1 minute data.
Grok was very helpful in identifying the winning strategies and to lump different strategies together into portfolios of strategies (20 strategies per portfolio); we created 4 different types of portfolios base on the out-of-sample results: the top 20 performers, the 20 with the highest sortino ratio, the 20 with the least correlation to each other and the 20 with the highest number of trades.
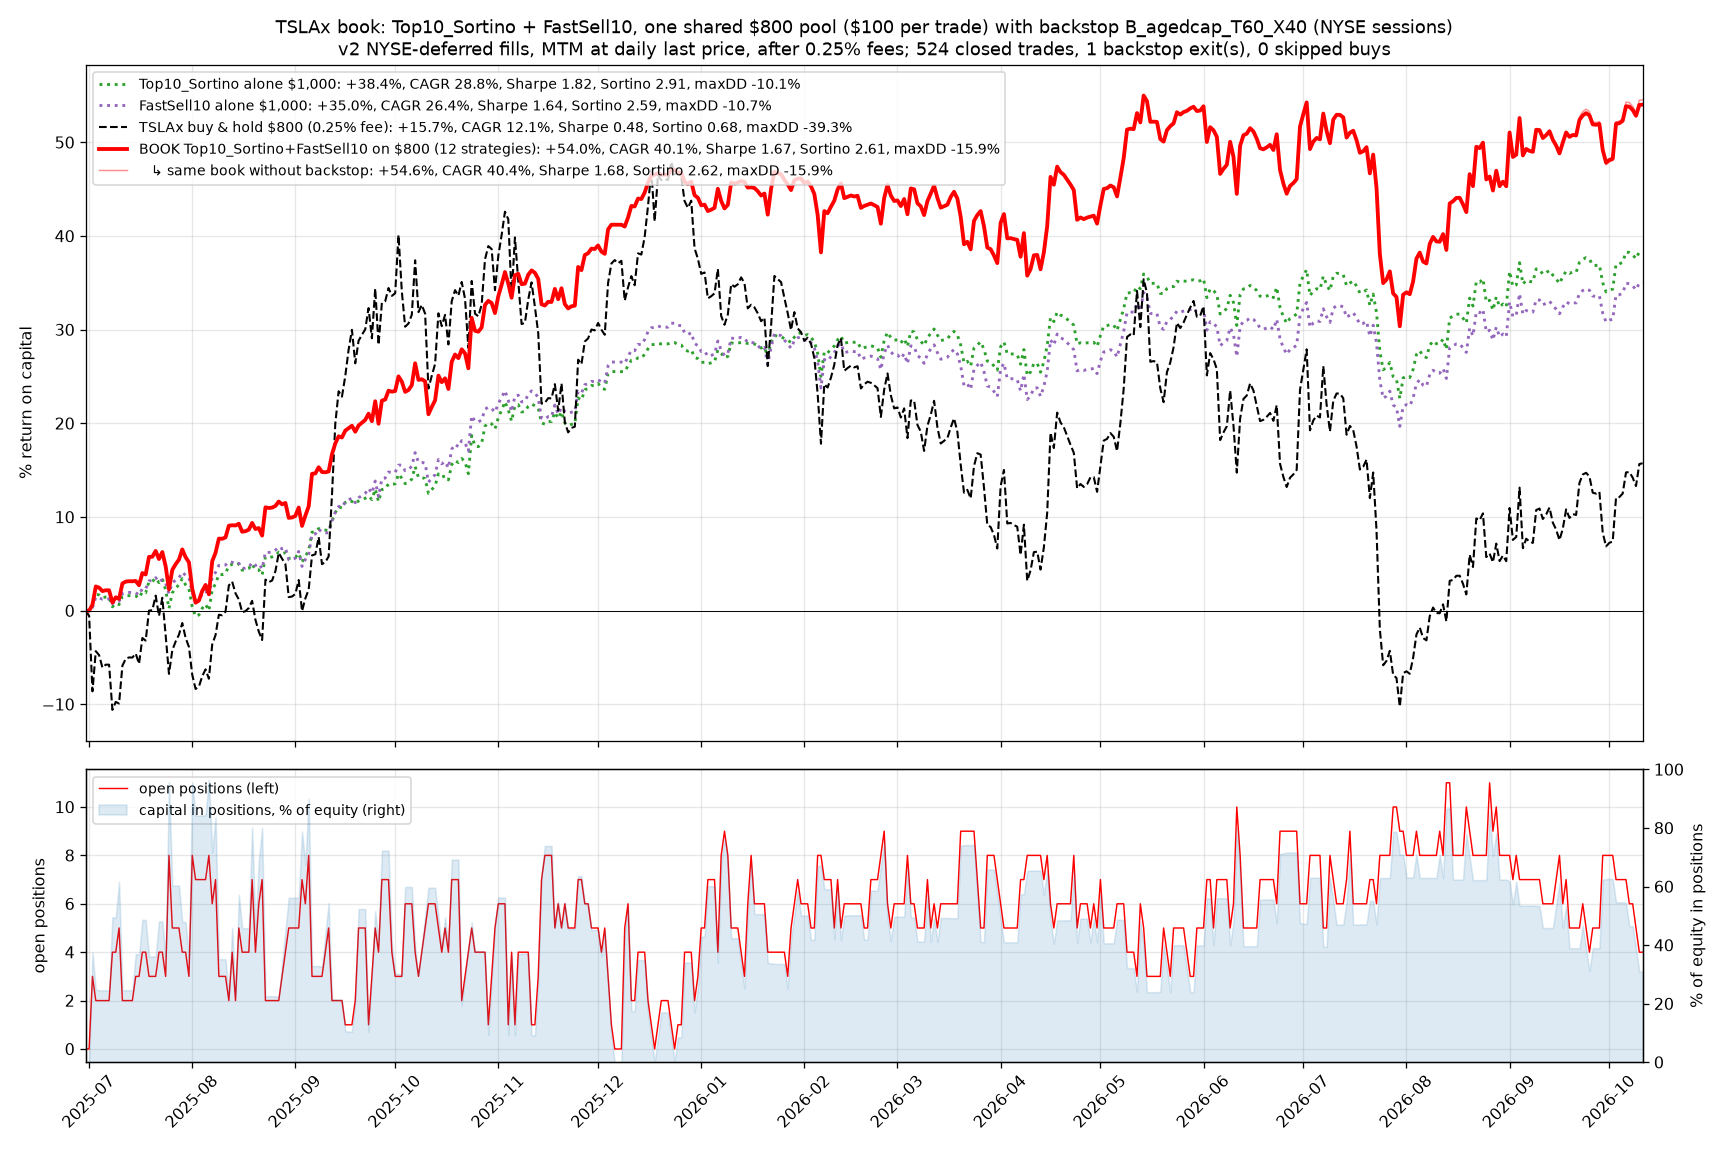
Grok Bot was then able to calculate the combined effect of lumping two or more portfolios of strategies together into a book of portfolios, thus minimizing draw-down. It then generated a complete live trading engine that I deployed on a Linux virtual private server to execute trades directly onchain on Solana, allowing to keep the cost for trading and slippage to less than 0.25% for a round-trip buy and sell operation.
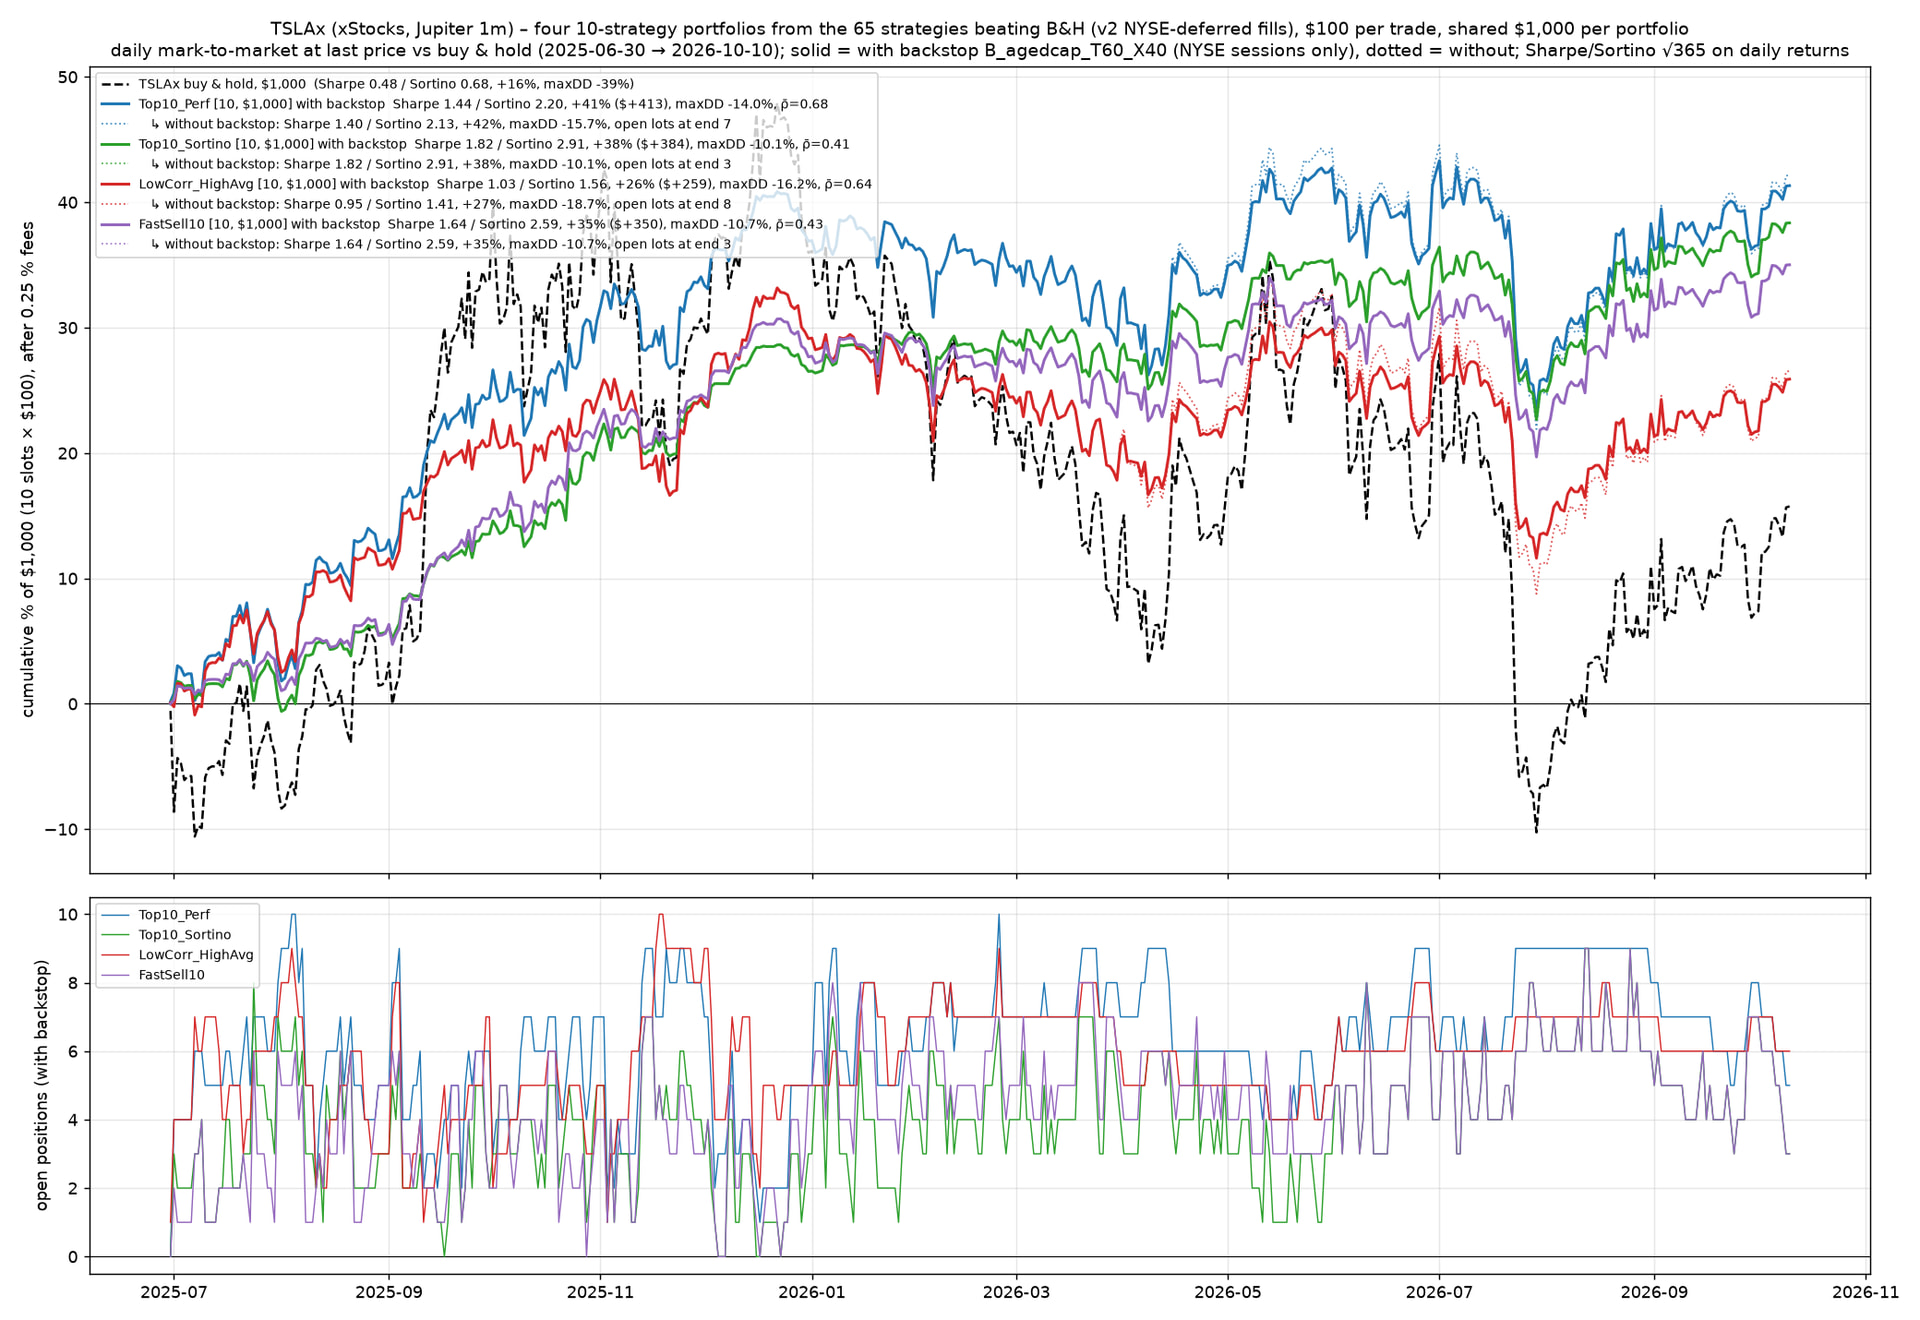
While I designed this primarily for crypto, it turns out to work well also for tokenized stocks but limited to those with high volume and high beta. Attached are examples of different portfolio of strategies performances for TSLAx versus a simple buy-and-hold strategy as well as an example of combining two portfolios into a better Sharpe & Sortino book of two portfolios.
I would be interested to know if some of you guys have designed similar systems and what your learnings are.
Best regards,
Florian